Rents: €14.31/sqm, up 1.3% year on year
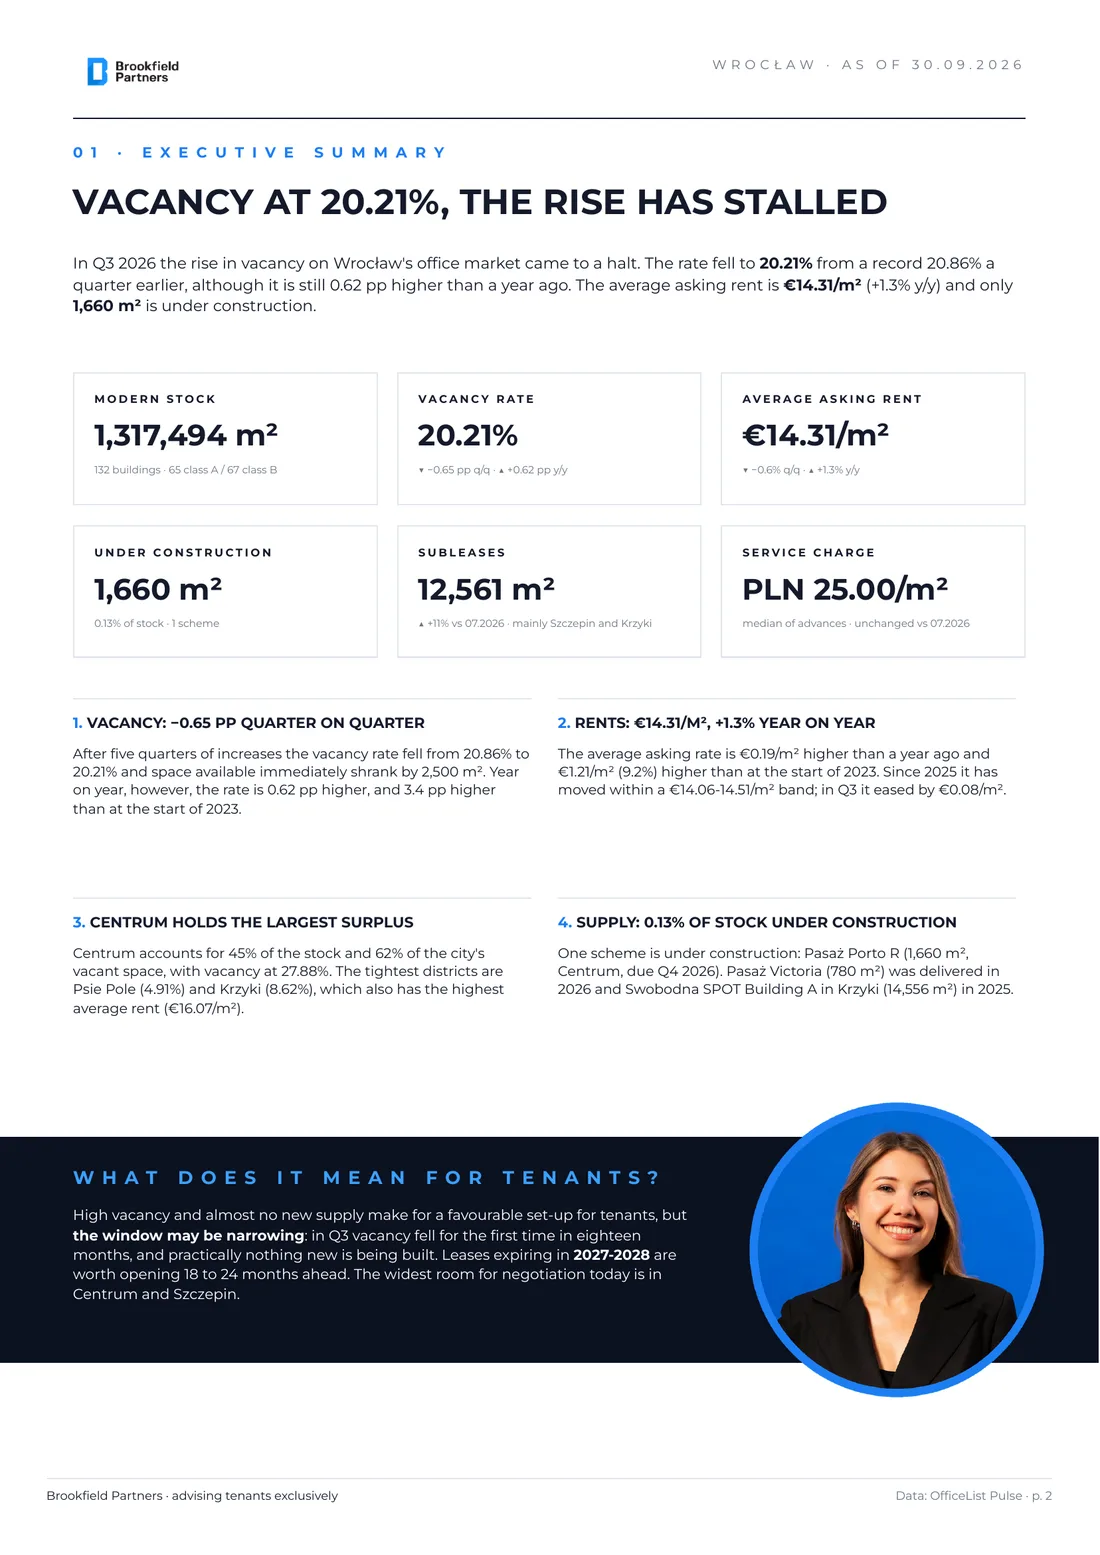
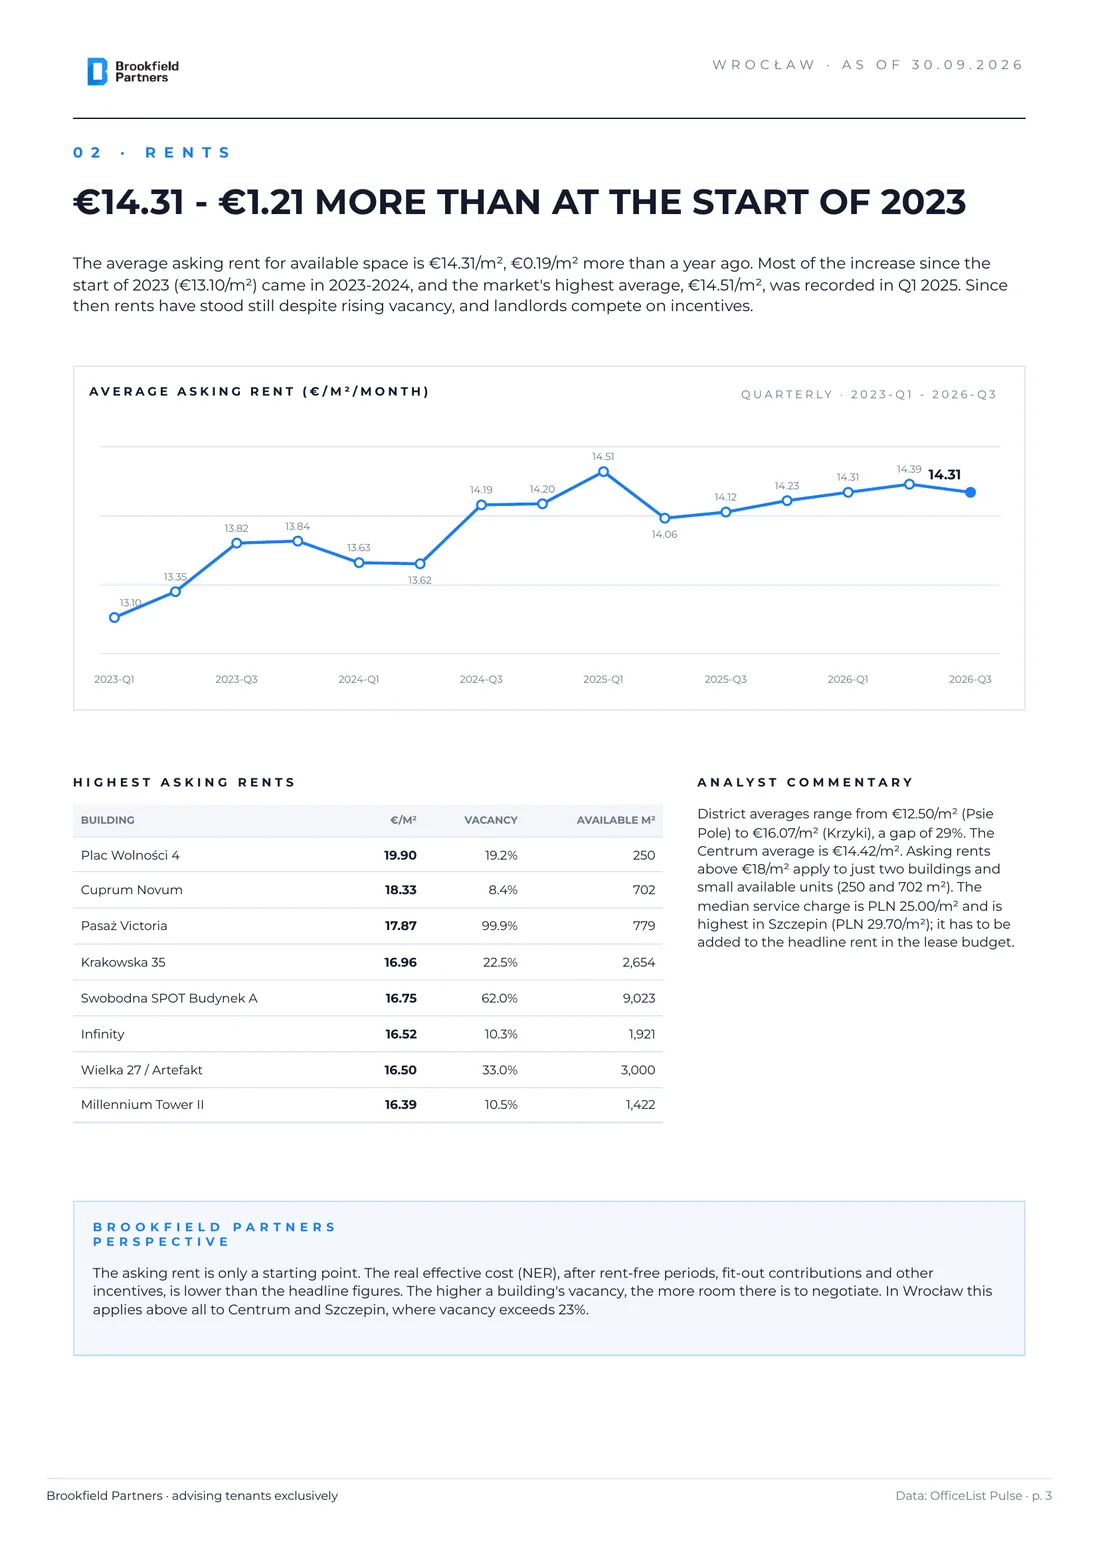
The average asking rent for available space is €14.31/sqm, €0.19/sqm more than in Q3 2025 (€14.12/sqm). Compared with the start of 2023, when it stood at €13.10/sqm, the rate is €1.21/sqm, or 9.2%, higher. Most of that increase came in 2023-2024, and the market's highest average, €14.51/sqm, was recorded in Q1 2025. Since then the rent has moved within a €14.06-14.51/sqm band despite rising vacancy, and landlords compete mainly on incentives. In Q3 2026 alone the rate eased by €0.08/sqm.
Average asking rent (€/sqm/month), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| €/sqm | 13.10 | 13.82 | 13.63 | 14.19 | 14.51 | 14.12 | 14.31 | 14.39 | 14.31 |
Highest asking rents
| Building | €/sqm | Vacancy | Available sqm |
|---|
| Plac Wolności 4 | 19.90 | 19.2% | 250 |
| Cuprum Novum | 18.33 | 8.4% | 702 |
| Pasaż Victoria | 17.87 | 99.9% | 779 |
| Krakowska 35 | 16.96 | 22.5% | 2,654 |
| Swobodna SPOT Budynek A | 16.75 | 62.0% | 9,023 |
| Infinity | 16.52 | 10.3% | 1,921 |
| Wielka 27 / Artefakt | 16.50 | 33.0% | 3,000 |
| Millennium Tower II | 16.39 | 10.5% | 1,422 |
District averages range from €12.50/sqm in Psie Pole to €16.07/sqm in Krzyki, a gap of 29%. The Centrum average is €14.42/sqm. Asking rents above €18/sqm apply to just two buildings and small available units (250 and 702 sqm). The median quoted service charge advance is PLN 25.00/sqm, highest in Szczepin at PLN 29.70/sqm. It has to be added to the headline rent in the lease budget.
Brookfield Partners perspective. The asking rent is only a starting point. The real effective cost (NER), after rent-free periods, fit-out contributions and other incentives, is lower than the headline figures. The higher a building's vacancy, the more room there is to negotiate. In Wrocław this applies above all to Centrum and Szczepin, where vacancy exceeds 23%.
Vacancy and availability: 20.21%, the first fall since early 2025
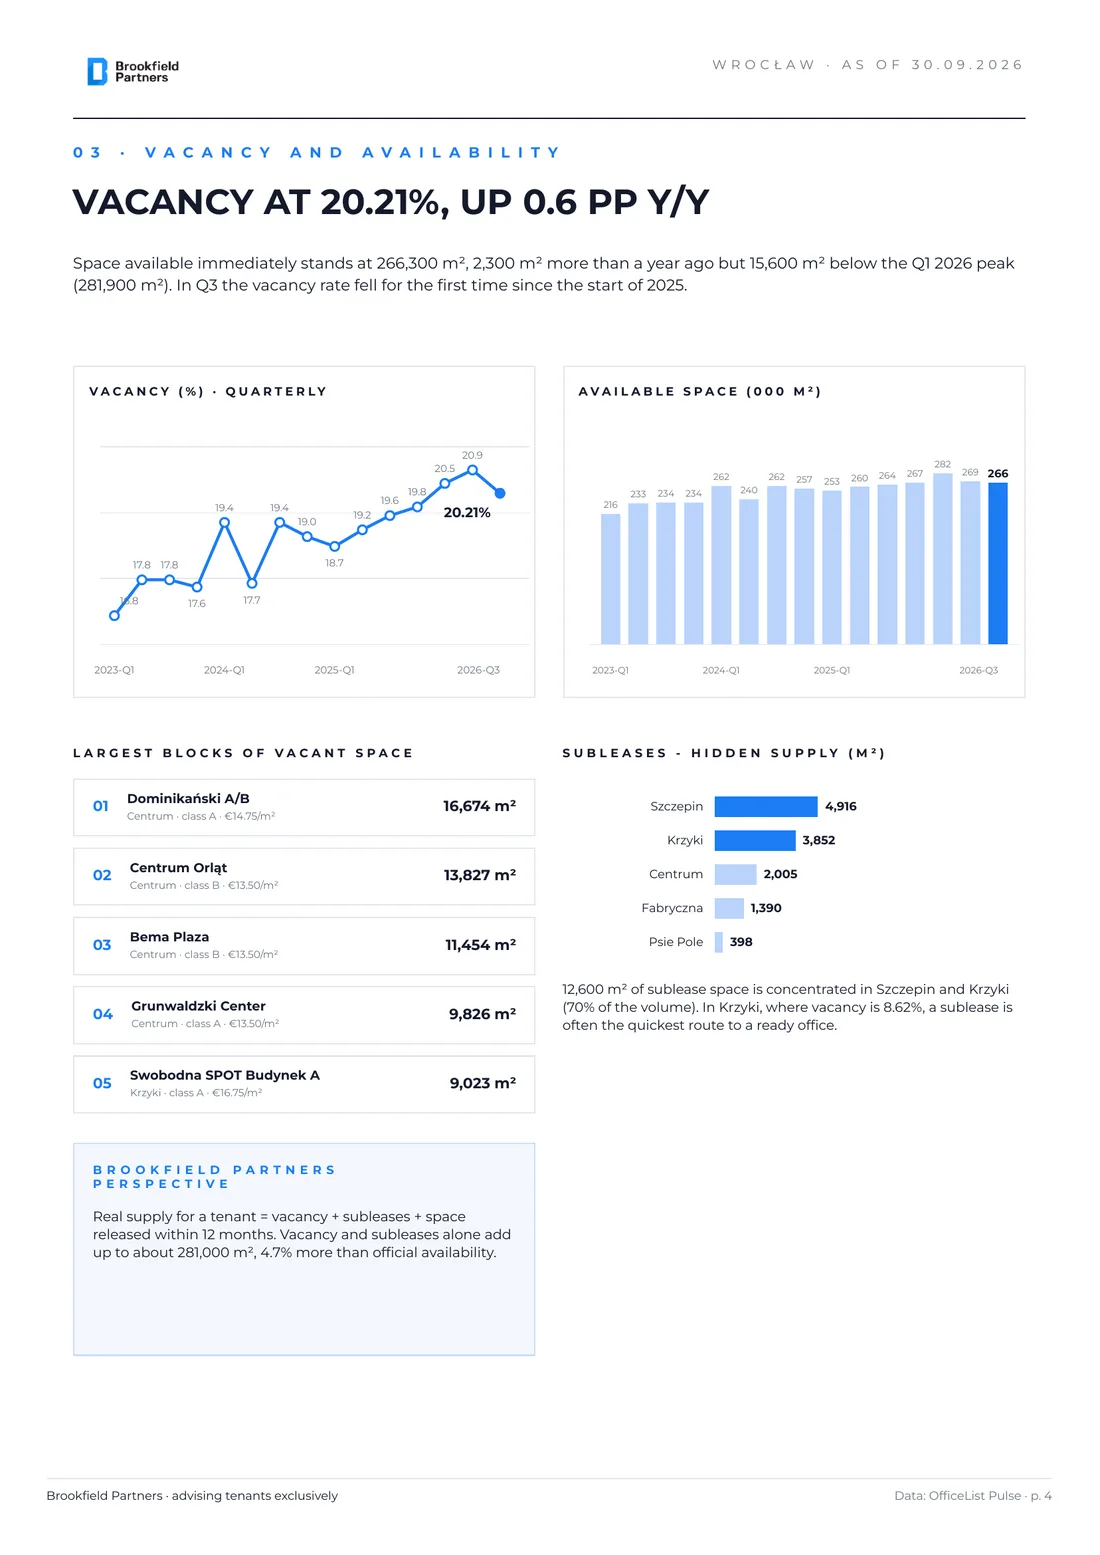
The vacancy rate fell from a record 20.86% in Q2 2026 to 20.21%, the first decline after five quarters of increases. Year on year, however, it is 0.62 pp higher (19.59% in Q3 2025), and 3.4 pp higher than at the start of 2023. Space available immediately stands at 266,300 sqm, 2,300 sqm more than a year ago but 15,600 sqm below the Q1 2026 peak (281,900 sqm).
Vacancy rate and available space, quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| Vacancy | 16.8% | 17.8% | 19.4% | 19.4% | 18.73% | 19.59% | 20.48% | 20.86% | 20.21% |
| Available (000 sqm) | 216 | 234 | 262 | 262 | 253 | 264 | 282 | 269 | 266 |
Largest concentrations of vacant space
| Building | District | Class | Rent €/sqm | Vacant sqm |
|---|
| Dominikański A/B | Centrum | A | 14.75 | 16,674 |
| Centrum Orląt | Centrum | B | 13.50 | 13,827 |
| Bema Plaza | Centrum | B | 13.50 | 11,454 |
| Grunwaldzki Center | Centrum | A | 13.50 | 9,826 |
| Swobodna SPOT Budynek A | Krzyki | A | 16.75 | 9,023 |
Four of the five largest blocks of vacant space are in Centrum. Sublease space totals 12,561 sqm, 70% of it in Szczepin (4,916 sqm) and Krzyki (3,852 sqm). In Krzyki, where vacancy is 8.62%, a sublease is often the quickest route to a ready office. Compared with July 2026 (11,300 sqm), sublease volume is up by about 11%.
Subleases - hidden supply by district (sqm)
| District | sqm |
|---|
| Szczepin | 4,916 |
| Krzyki | 3,852 |
| Centrum | 2,005 |
| Fabryczna | 1,390 |
| Psie Pole | 398 |
Brookfield Partners perspective. Real supply for a tenant is vacancy plus subleases plus space released within twelve months. Vacancy and subleases alone total around 281,000 sqm, 4.7% more than official availability.
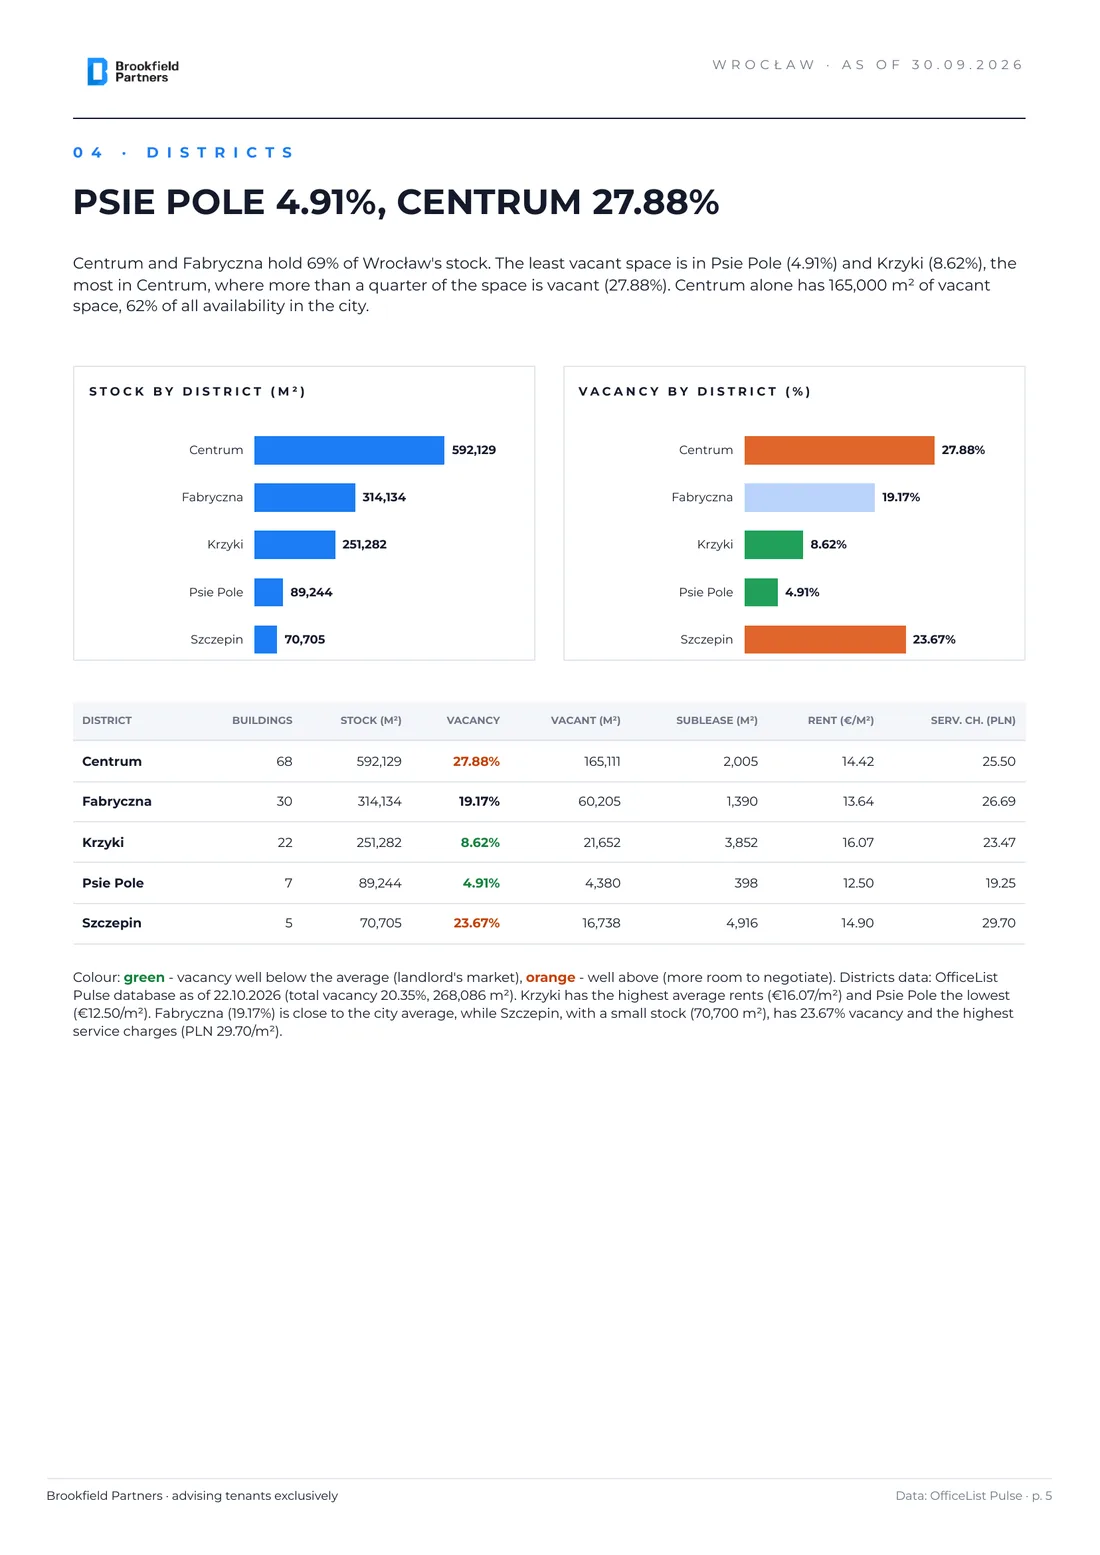
Districts: Psie Pole at 4.91%, Centrum at 27.88%
Centrum and Fabryczna hold 69% of Wrocław's stock. The least vacant space is in Psie Pole (4.91%) and Krzyki (8.62%), which also has the highest average rent in the city (€16.07/sqm). Centrum has the most vacant offices: vacancy there is 27.88%, and its 165,000 sqm of vacant space is 62% of all availability in Wrocław. Fabryczna (19.17%) is close to the city average, while Szczepin, with a small stock (70,700 sqm), has 23.67% vacancy and the highest service charges.
Wrocław office market by district (database as of 22.10.2026)
| District | Buildings | Stock (sqm) | Vacancy | Vacant (sqm) | Sublease (sqm) | Rent (€/sqm) | Serv. charge (PLN) |
|---|
| Centrum | 68 | 592,129 | 27.88% | 165,111 | 2,005 | 14.42 | 25.50 |
| Fabryczna | 30 | 314,134 | 19.17% | 60,205 | 1,390 | 13.64 | 26.69 |
| Krzyki | 22 | 251,282 | 8.62% | 21,652 | 3,852 | 16.07 | 23.47 |
| Psie Pole | 7 | 89,244 | 4.91% | 4,380 | 398 | 12.50 | 19.25 |
| Szczepin | 5 | 70,705 | 23.67% | 16,738 | 4,916 | 14.90 | 29.70 |
Rent is the average asking rate for available space; the service charge is the median of quoted advances. District data reflect the database as of 22 October 2026 (total vacancy 20.35%, 268,086 sqm).
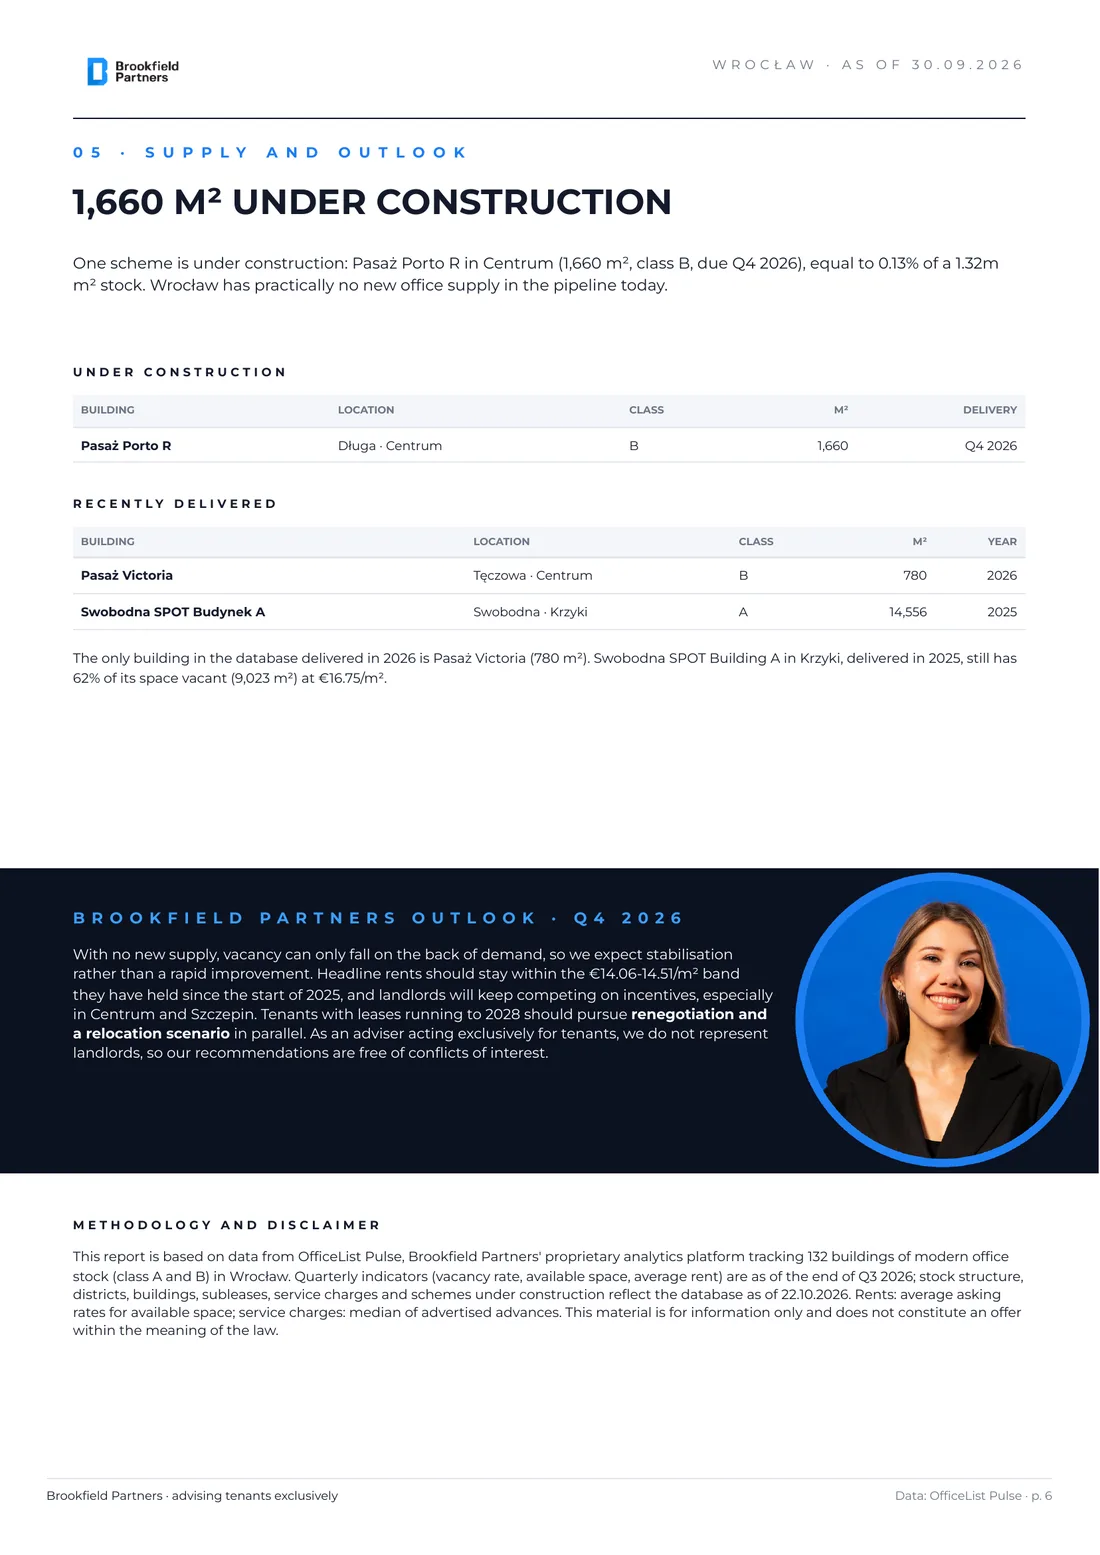
Supply: 1,660 sqm under construction, 0.13% of stock
One scheme is under construction: Pasaż Porto R in Centrum (1,660 sqm, class B, due Q4 2026). Wrocław has practically no new office supply in the pipeline today. The only building delivered in 2026 is Pasaż Victoria (780 sqm). Swobodna SPOT Building A in Krzyki (14,556 sqm), delivered in 2025, still has 62% of its space vacant, or 9,023 sqm, at €16.75/sqm.
Under construction
| Building | Location | Class | sqm | Completion |
|---|
| Pasaż Porto R | Długa · Centrum | B | 1,660 | Q4 2026 |
Recently delivered
| Building | Location | Class | sqm | Year |
|---|
| Pasaż Victoria | Tęczowa · Centrum | B | 780 | 2026 |
| Swobodna SPOT Budynek A | Swobodna · Krzyki | A | 14,556 | 2025 |
Brookfield Partners outlook for Q4 2026. With no new supply, vacancy can only fall on the back of demand, so we expect stabilisation rather than a rapid improvement. Headline rents should stay within the €14.06-14.51/sqm band they have held since the start of 2025, and landlords will keep competing on incentives, especially in Centrum and Szczepin. For tenants with leases expiring by 2028 we recommend running a renegotiation and a relocation scenario in parallel. As an adviser acting exclusively for tenants we do not represent landlords, so our recommendations are free of any conflict of interest.
Methodology
The report is based on OfficeList Pulse data, Brookfield Partners' proprietary analytics platform monitoring 132 modern office buildings in Wrocław (65 class A and 67 class B). Quarterly indicators (vacancy rate, available space, average rent) are end-of-Q3 2026 values. Stock structure, districts, buildings, subleases, service charges and schemes under construction reflect the database as of 22 October 2026. Rents are average asking rates for available space; service charges are the median of quoted advances. This material is for information only and does not constitute an offer within the meaning of the law.