Rents: €17.52/sqm, the highest in the quarterly series
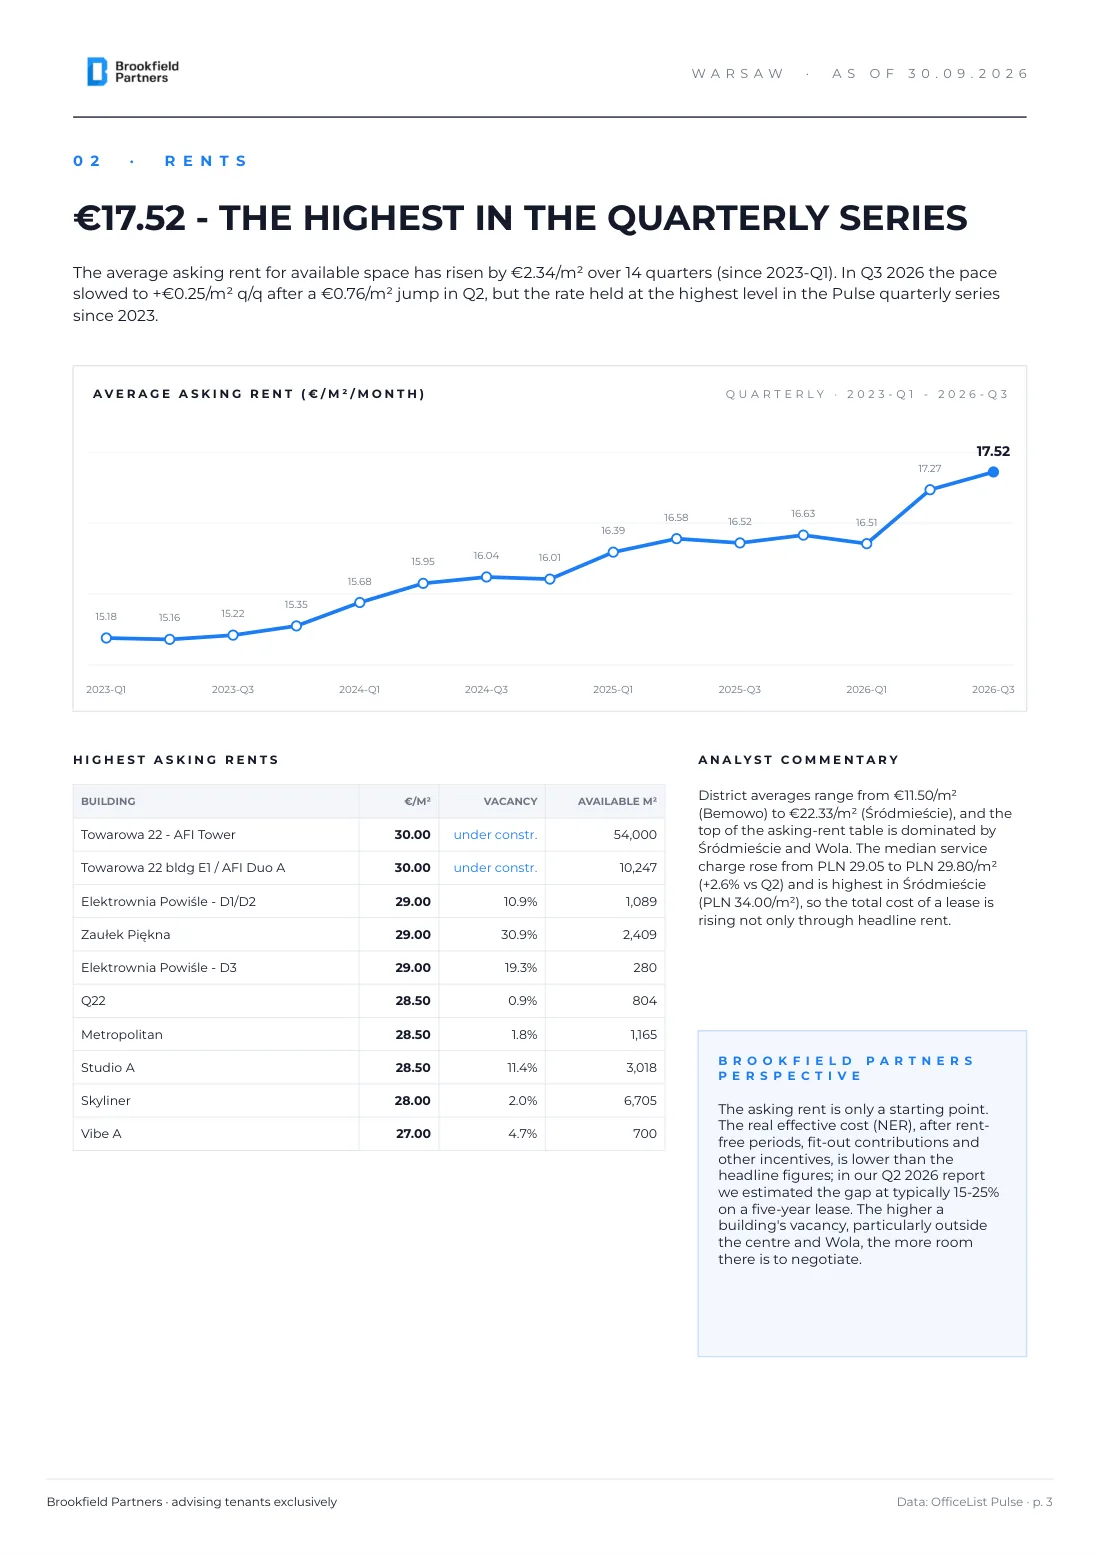
The average asking rent for available space has risen by €2.34/sqm since the start of 2023, an increase of 15%. In the third quarter of 2026 the pace slowed to +€0.25/sqm quarter on quarter after a €0.76/sqm jump in the previous quarter, but the rate held at the highest level in the Pulse quarterly series. The top asking rents reach €27-30/sqm.
Average asking rent (€/sqm/month), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| €/sqm | 15.18 | 15.22 | 15.68 | 16.04 | 16.39 | 16.52 | 16.51 | 17.27 | 17.52 |
Highest asking rents
| Building | €/sqm | Vacancy | Available sqm |
|---|
| Towarowa 22 - AFI Tower | 30.00 | under construction | 54,000 |
| Towarowa 22 bldg E1 / AFI Duo A | 30.00 | under construction | 10,247 |
| Elektrownia Powiśle - D1/D2 | 29.00 | 10.9% | 1,089 |
| Zaułek Piękna | 29.00 | 30.9% | 2,409 |
| Elektrownia Powiśle - D3 | 29.00 | 19.3% | 280 |
| Q22 | 28.50 | 0.9% | 804 |
| Metropolitan | 28.50 | 1.8% | 1,165 |
| Studio A | 28.50 | 11.4% | 3,018 |
| Skyliner | 28.00 | 2.0% | 6,705 |
| Vibe A | 27.00 | 4.7% | 700 |
District averages range from €11.50/sqm in Bemowo to €22.33/sqm in Śródmieście, and the top of the asking-rent table is dominated by Śródmieście and Wola. The second component of the bill is rising too: the median quoted service charge advance increased from PLN 29.05 to PLN 29.80/sqm, up 2.6% quarter on quarter, and is highest in Śródmieście at PLN 34.00/sqm.
Brookfield Partners perspective. The asking rent is only a starting point. The net effective rent, once rent-free periods, fit-out contributions and other incentives are taken into account, is lower than the headline figure; in our Q2 2026 report we estimated that gap at typically 15-25% on a five-year lease. The higher a building's vacancy, particularly outside the centre and Wola, the more room there is to negotiate.
Vacancy and availability: 7.52% and a second quarter of declines
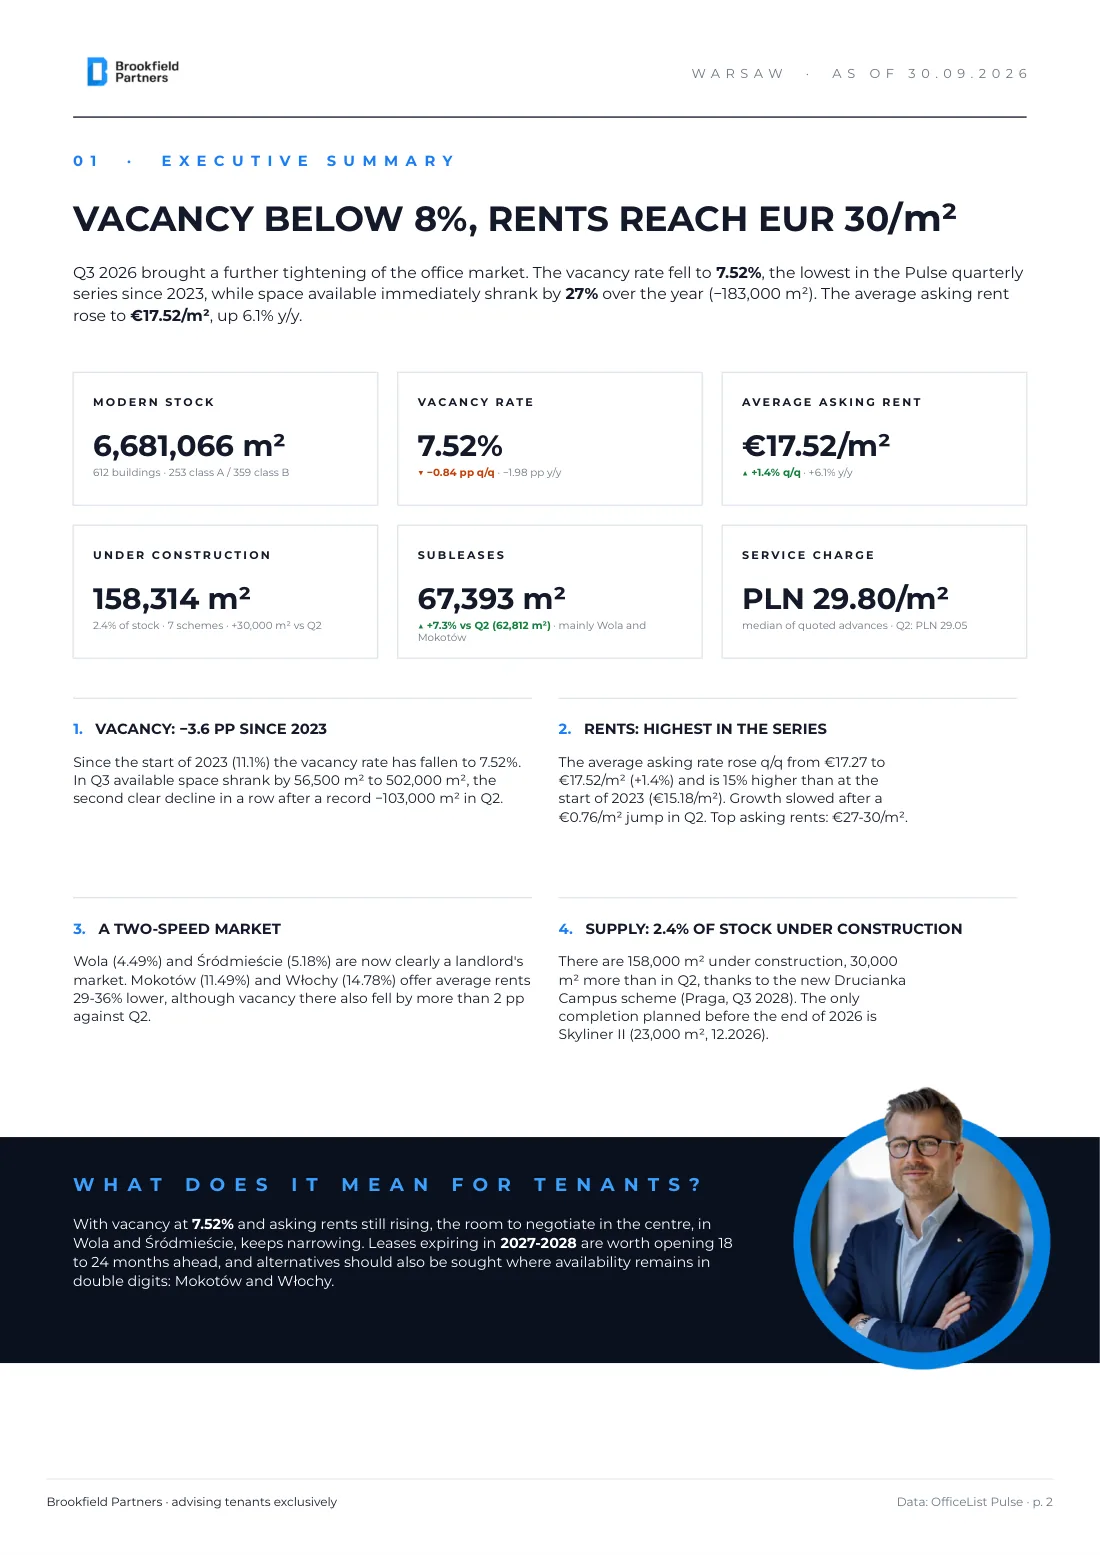
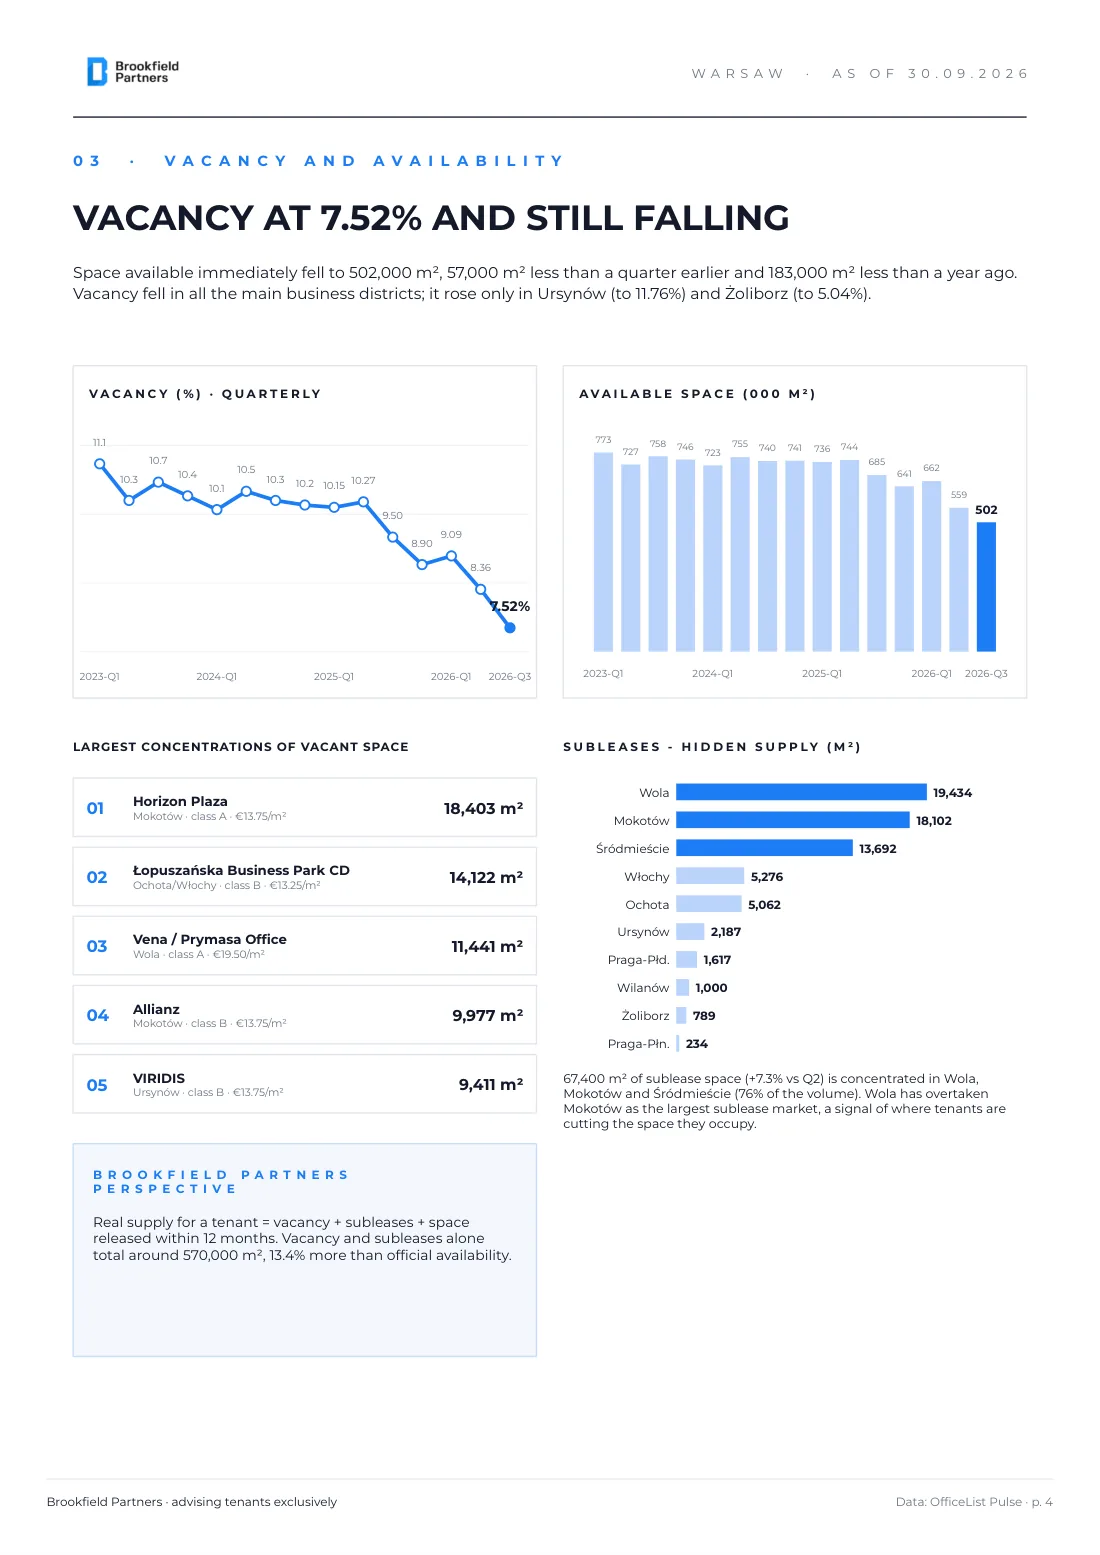
The vacancy rate fell to 7.52%, down 0.84 pp quarter on quarter and 1.98 pp year on year, the lowest level in the Pulse quarterly series that began in 2023. Space available immediately shrank to 502,000 sqm, 57,000 sqm less than a quarter earlier and 183,000 sqm less than a year ago, a decline of 27% year on year. This is the second clear drop in a row after a record loss of 103,000 sqm in the second quarter. Vacancy fell across all the main business districts and rose only in Ursynów, to 11.76%, and Żoliborz, to 5.04%.
Vacancy rate and available space, quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| Vacancy | 11.1% | 10.7% | 10.1% | 10.3% | 10.15% | 9.50% | 9.09% | 8.36% | 7.52% |
| Available (000 sqm) | 773 | 758 | 723 | 740 | 736 | 685 | 662 | 559 | 502 |
Largest concentrations of vacant space
| Building | Location | Class | Rent €/sqm | Vacant sqm |
|---|
| Horizon Plaza | Mokotów | A | 13.75 | 18,403 |
| Łopuszańska Business Park CD | Ochota / Włochy | B | 13.25 | 14,122 |
| Vena / Prymasa Office | Wola | A | 19.50 | 11,441 |
| Allianz | Mokotów | B | 13.75 | 9,977 |
| VIRIDIS | Ursynów | B | 13.75 | 9,411 |
Hidden supply is growing in parallel. There are 67,393 sqm on the sublease market, 7.3% more than in the second quarter, when the figure was 62,812 sqm. Three quarters of that volume, 76% to be precise, sits in Wola, Mokotów and Śródmieście, with Wola overtaking Mokotów as the largest sublease market. That is a clear signal of where tenants are cutting the space they occupy.
Subleases - hidden supply by district (sqm)
| District | sqm |
|---|
| Wola | 19,434 |
| Mokotów | 18,102 |
| Śródmieście | 13,692 |
| Włochy | 5,276 |
| Ochota | 5,062 |
| Ursynów | 2,187 |
| Praga-Południe | 1,617 |
| Wilanów | 1,000 |
| Żoliborz | 789 |
| Praga-Północ | 234 |
Brookfield Partners perspective. Real supply for a tenant is vacancy plus subleases plus space being released within a twelve-month horizon. Vacancy and subleases alone add up to around 570,000 sqm, 13.4% more than the official availability figure suggests.
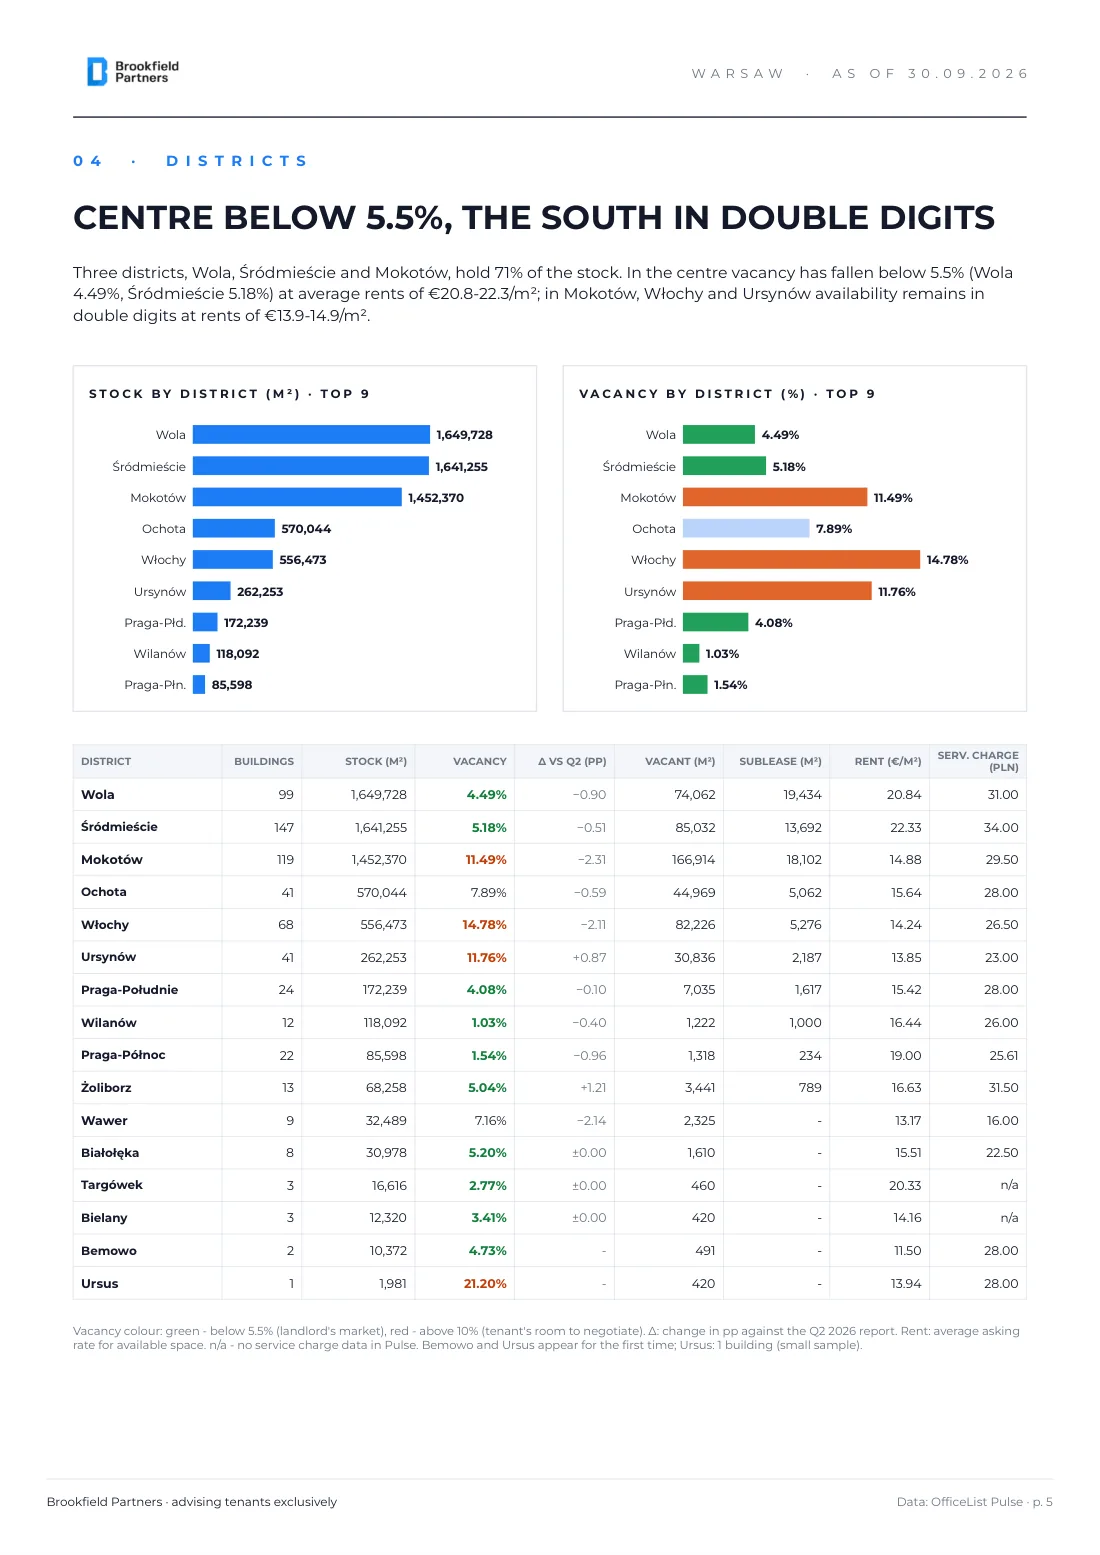
Districts: the centre below 5.5%, the south in double digits
Wola, Śródmieście and Mokotów hold 71% of Warsaw's stock. In the centre vacancy has dropped below 5.5%, with Wola at 4.49% and Śródmieście at 5.18%, at average rents of €20.84 to €22.33/sqm. In Mokotów, Włochy and Ursynów availability remains in double digits at rents of €13.85 to €14.88/sqm, which is 29-36% lower than in the centre. Even there, however, vacancy fell by more than 2 pp over the quarter.
Warsaw office market by district (as of 30.09.2026)
| District | Buildings | Stock (sqm) | Vacancy | Δ vs Q2 (pp) | Vacant (sqm) | Sublease (sqm) | Rent (€/sqm) | Service charge (PLN) |
|---|
| Wola | 99 | 1,649,728 | 4.49% | −0.90 | 74,062 | 19,434 | 20.84 | 31.00 |
| Śródmieście | 147 | 1,641,255 | 5.18% | −0.51 | 85,032 | 13,692 | 22.33 | 34.00 |
| Mokotów | 119 | 1,452,370 | 11.49% | −2.31 | 166,914 | 18,102 | 14.88 | 29.50 |
| Ochota | 41 | 570,044 | 7.89% | −0.59 | 44,969 | 5,062 | 15.64 | 28.00 |
| Włochy | 68 | 556,473 | 14.78% | −2.11 | 82,226 | 5,276 | 14.24 | 26.50 |
| Ursynów | 41 | 262,253 | 11.76% | +0.87 | 30,836 | 2,187 | 13.85 | 23.00 |
| Praga-Południe | 24 | 172,239 | 4.08% | −0.10 | 7,035 | 1,617 | 15.42 | 28.00 |
| Wilanów | 12 | 118,092 | 1.03% | −0.40 | 1,222 | 1,000 | 16.44 | 26.00 |
| Praga-Północ | 22 | 85,598 | 1.54% | −0.96 | 1,318 | 234 | 19.00 | 25.61 |
| Żoliborz | 13 | 68,258 | 5.04% | +1.21 | 3,441 | 789 | 16.63 | 31.50 |
| Wawer | 9 | 32,489 | 7.16% | −2.14 | 2,325 | - | 13.17 | 16.00 |
| Białołęka | 8 | 30,978 | 5.20% | ±0.00 | 1,610 | - | 15.51 | 22.50 |
| Targówek | 3 | 16,616 | 2.77% | ±0.00 | 460 | - | 20.33 | n/a |
| Bielany | 3 | 12,320 | 3.41% | ±0.00 | 420 | - | 14.16 | n/a |
| Bemowo | 2 | 10,372 | 4.73% | - | 491 | - | 11.50 | 28.00 |
| Ursus | 1 | 1,981 | 21.20% | - | 420 | - | 13.94 | 28.00 |
Δ is the change in percentage points against the Q2 2026 report. Rent is the average asking rate for available space, and n/a means no service charge data in Pulse. Bemowo and Ursus appear in the table for the first time; Ursus represents a single building, so the sample is small.
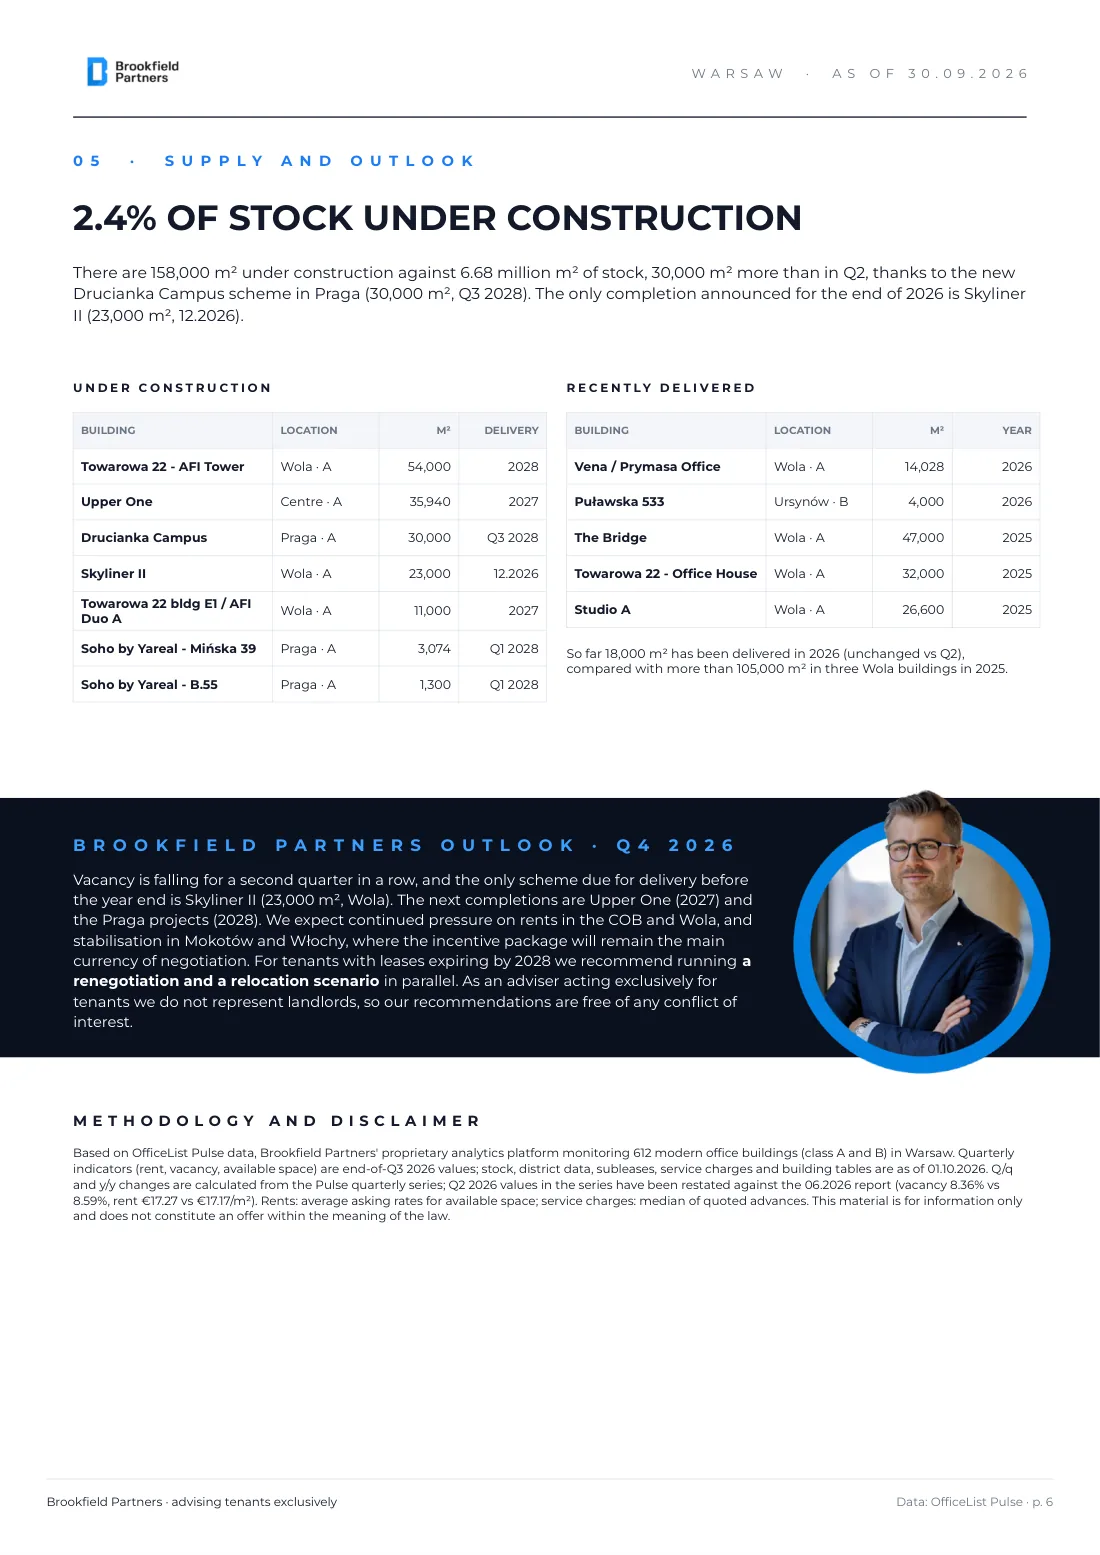
Supply and outlook: 2.4% of stock under construction
There are 158,314 sqm under construction against a stock of 6.68 million sqm, 30,000 sqm more than in the second quarter. The increase comes from a single new scheme, Drucianka Campus in Praga, due to deliver 30,000 sqm in the third quarter of 2028. The only completion announced for the remainder of 2026 is Skyliner II, 23,000 sqm in Wola. So far 18,000 sqm has been delivered in 2026, unchanged from the previous report, against more than 105,000 sqm in three Wola buildings in 2025.
Under construction
| Building | Location | sqm | Delivery |
|---|
| Towarowa 22 - AFI Tower | Wola · A | 54,000 | 2028 |
| Upper One | Centre · A | 35,940 | 2027 |
| Drucianka Campus | Praga · A | 30,000 | Q3 2028 |
| Skyliner II | Wola · A | 23,000 | 12.2026 |
| Towarowa 22 bldg E1 / AFI Duo A | Wola · A | 11,000 | 2027 |
| Soho by Yareal - Mińska 39 | Praga · A | 3,074 | Q1 2028 |
| Soho by Yareal - B.55 | Praga · A | 1,300 | Q1 2028 |
Recently delivered
| Building | Location | sqm | Year |
|---|
| Vena / Prymasa Office | Wola · A | 14,028 | 2026 |
| Puławska 533 | Ursynów · B | 4,000 | 2026 |
| The Bridge | Wola · A | 47,000 | 2025 |
| Towarowa 22 - Office House | Wola · A | 32,000 | 2025 |
| Studio A | Wola · A | 26,600 | 2025 |
Brookfield Partners perspective (Q4 2026). Vacancy is falling for a second consecutive quarter and the only scheme due for delivery before the year ends is Skyliner II. The next completions are Upper One in 2027 and the Praga projects in 2028. We expect continued pressure on rents in the COB and Wola, and stabilisation in Mokotów and Włochy, where the incentive package will remain the main currency of negotiation. For tenants with leases expiring by 2028 we recommend running a renegotiation and a relocation scenario in parallel. As an adviser acting exclusively for tenants we do not represent landlords, so our recommendations are free of any conflict of interest.
Methodology
The report is based on OfficeList Pulse data, Brookfield Partners' proprietary analytics platform monitoring 612 modern class A and B office buildings in Warsaw. Quarterly indicators, meaning rent, vacancy and available space, are given as at the end of the third quarter of 2026, while stock, district data, subleases, service charges and building tables reflect the position on 1 October 2026. Quarter-on-quarter and year-on-year changes are calculated from the Pulse quarterly series, in which the Q2 2026 values have been restated against the June 2026 report: vacancy now reads 8.36% against the 8.59% published earlier, and rent €17.27 against €17.17/sqm. Rents are average asking rates for available space and service charges are the median of quoted advances. This material is informational and does not constitute an offer within the meaning of the law.