Rents: €14.39/sqm, virtually flat year on year
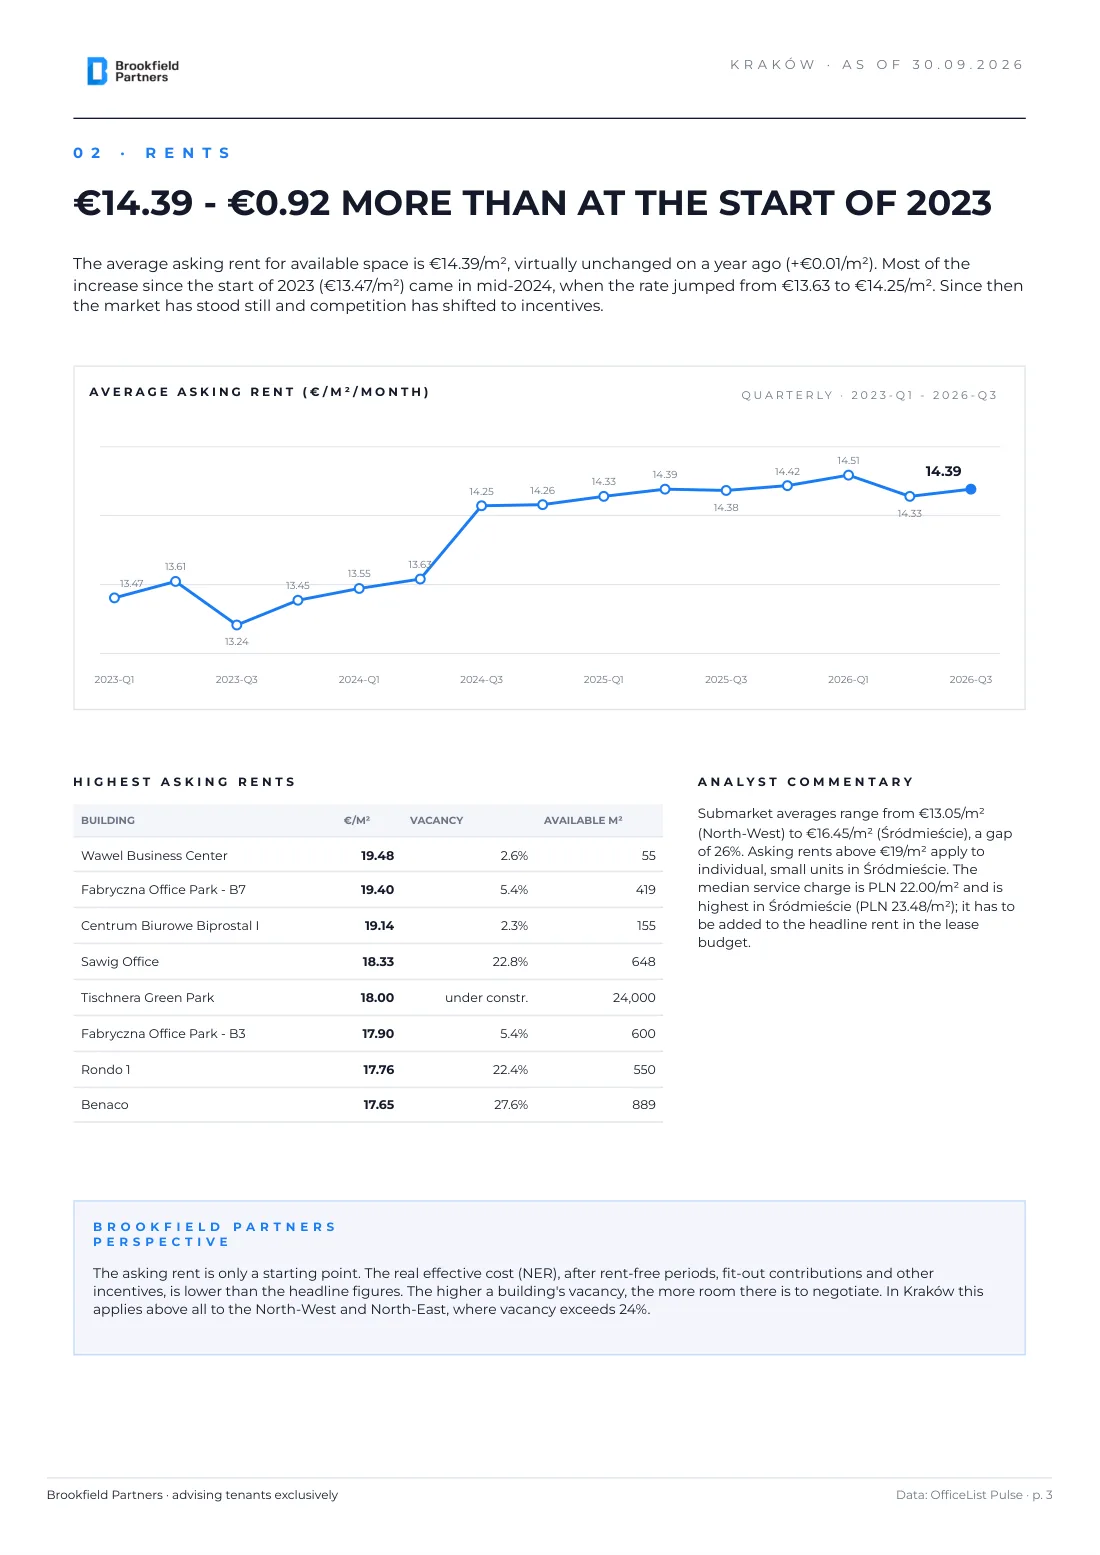
The average asking rent for available space is €14.39/sqm, in line with a year ago (€14.38/sqm in Q3 2025). Compared with the start of 2023, when it stood at €13.47/sqm, the rate is €0.92/sqm, or 6.8%, higher. Almost all of that increase came in mid-2024, when the rent jumped from €13.63 to €14.25/sqm. Since then it has moved within a narrow €14.25-14.51/sqm band, and landlords now compete mainly on incentives.
Average asking rent (€/sqm/month), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| €/sqm | 13.47 | 13.24 | 13.55 | 14.25 | 14.33 | 14.38 | 14.51 | 14.33 | 14.39 |
Highest asking rents
| Building | €/sqm | Vacancy | Available sqm |
|---|
| Wawel Business Center | 19.48 | 2.6% | 55 |
| Fabryczna Office Park - B7 | 19.40 | 5.4% | 419 |
| Centrum Biurowe Biprostal I | 19.14 | 2.3% | 155 |
| Sawig Office | 18.33 | 22.8% | 648 |
| Tischnera Green Park | 18.00 | under construction | 24,000 |
| Fabryczna Office Park - B3 | 17.90 | 5.4% | 600 |
| Rondo 1 | 17.76 | 22.4% | 550 |
| Benaco | 17.65 | 27.6% | 889 |
Submarket averages range from €13.05/sqm in the North-West to €16.45/sqm in Śródmieście, a gap of 26%. Asking rents above €19/sqm apply to individual, small units in Śródmieście. The median quoted service charge advance is PLN 22.00/sqm, highest in Śródmieście at PLN 23.48/sqm. It has to be added to the headline rent in the lease budget.
Brookfield Partners perspective. The asking rent is only a starting point. The real effective cost (NER), after rent-free periods, fit-out contributions and other incentives, is lower than the headline figures. The higher a building's vacancy, the more room there is to negotiate. In Kraków this applies above all to the North-West and North-East, where vacancy exceeds 24%.
Vacancy and availability: 18.07%, the lowest since 2023
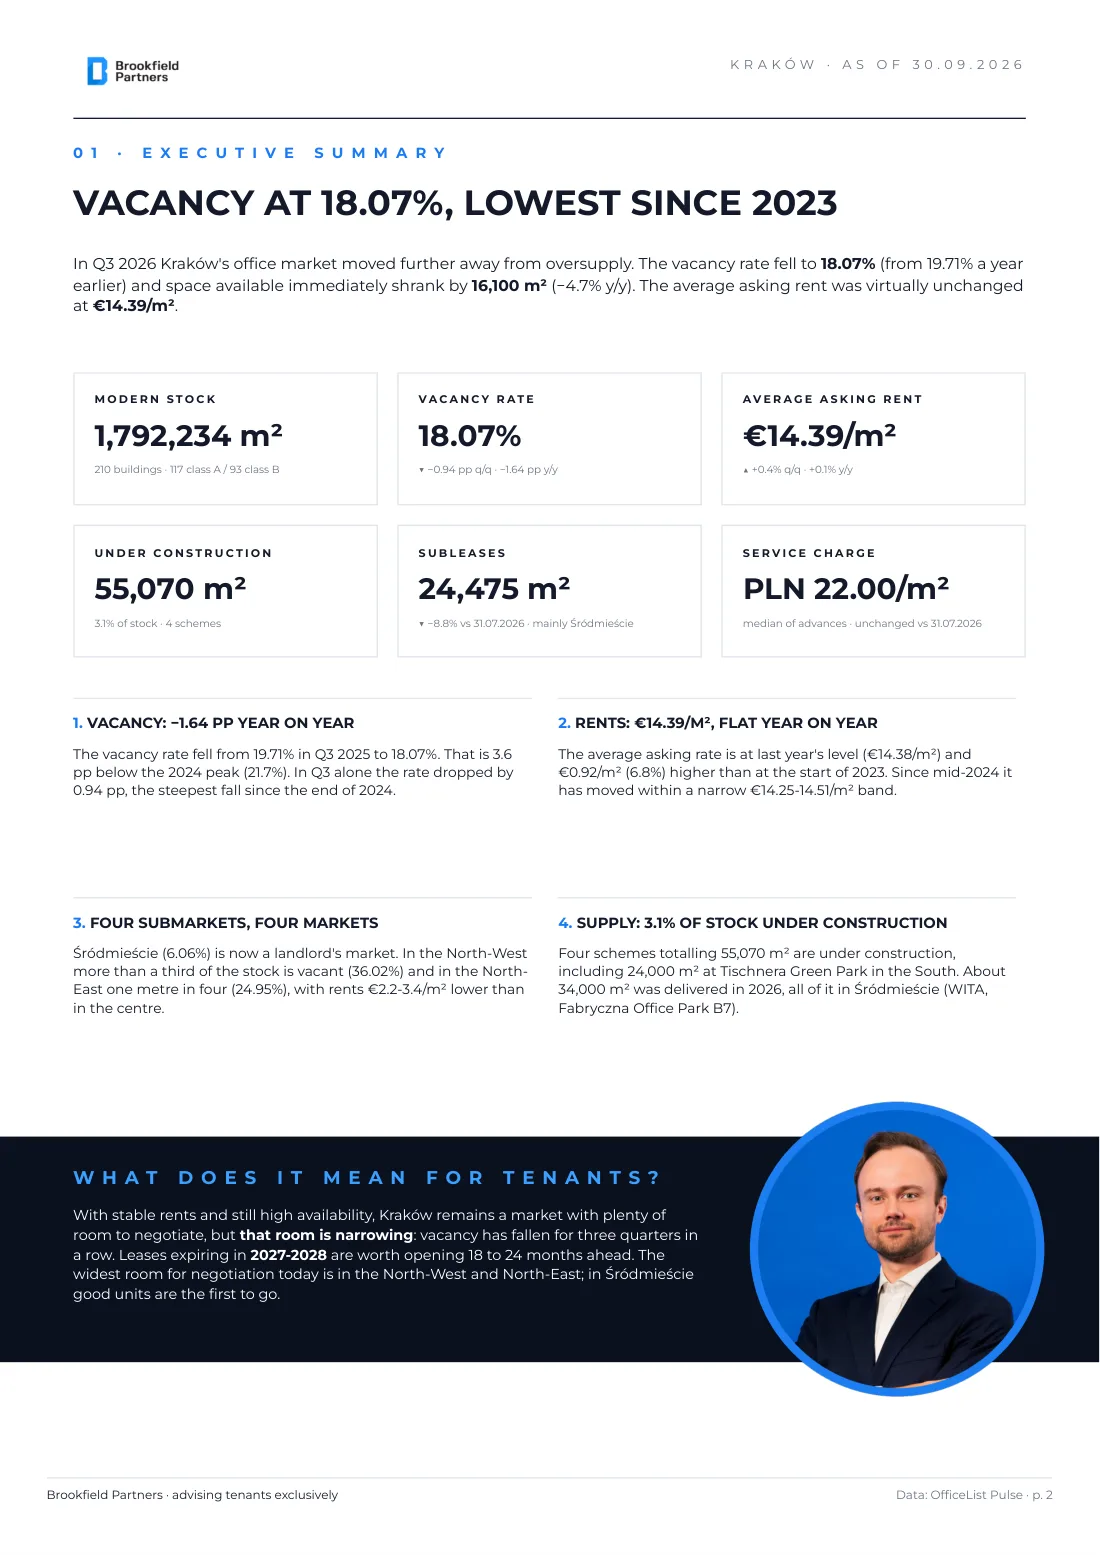
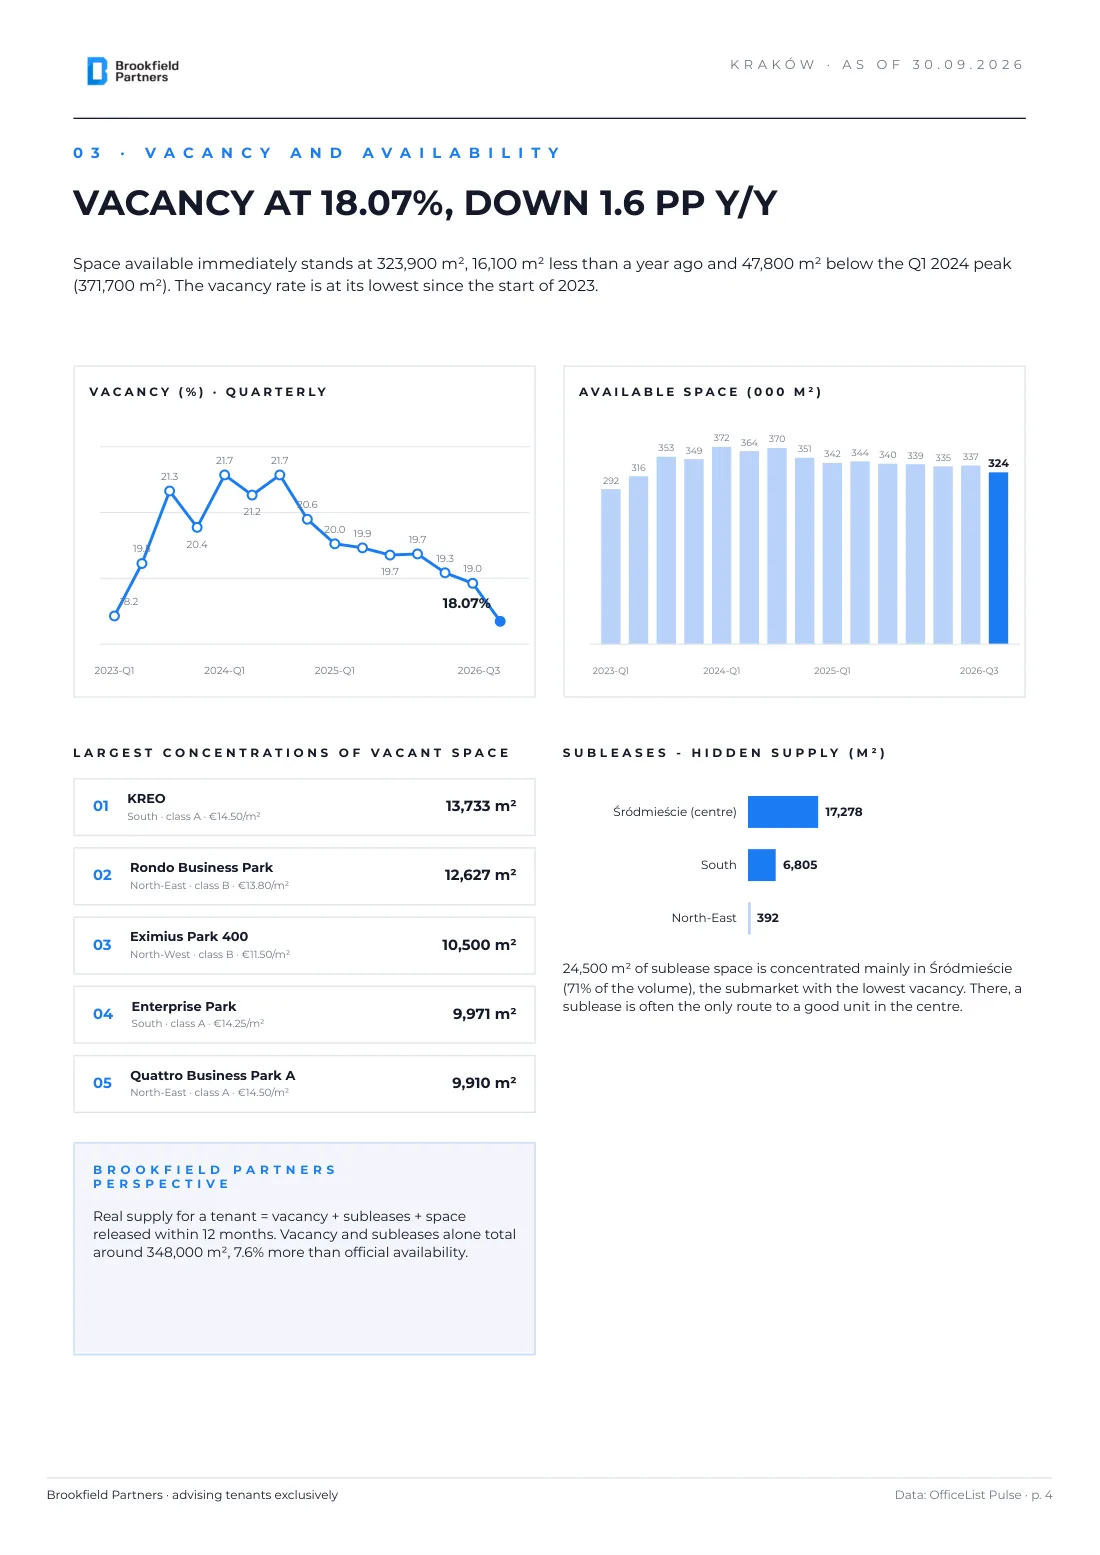
The vacancy rate fell from 19.71% in Q3 2025 to 18.07%. That is 3.6 pp below the 2024 peak of 21.7%, and in Q3 2026 alone the rate dropped by 0.94 pp, the steepest fall since the end of 2024. Vacancy has now declined for three quarters in a row. Space available immediately stands at 323,900 sqm, 16,100 sqm less than a year ago and 47,800 sqm below the Q1 2024 peak.
Vacancy rate and available space, quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| Vacancy | 18.2% | 21.3% | 21.7% | 21.7% | 19.99% | 19.71% | 19.27% | 19.01% | 18.07% |
| Available (000 sqm) | 292 | 353 | 372 | 370 | 342 | 340 | 335 | 337 | 324 |
Largest concentrations of vacant space
| Building | Submarket | Class | Rent €/sqm | Vacant sqm |
|---|
| KREO | South | A | 14.50 | 13,733 |
| Rondo Business Park | North-East | B | 13.80 | 12,627 |
| Eximius Park 400 | North-West | B | 11.50 | 10,500 |
| Enterprise Park | South | A | 14.25 | 9,971 |
| Quattro Business Park A | North-East | A | 14.50 | 9,910 |
Sublease space totals 24,475 sqm, 71% of it in Śródmieście (17,278 sqm), the submarket with the lowest vacancy. There, a sublease is often the only route to a good unit in the centre. Compared with 31 July 2026 (26,839 sqm), sublease volume is down 8.8%.
Subleases - hidden supply by submarket (sqm)
| Submarket | sqm |
|---|
| Śródmieście | 17,278 |
| South | 6,805 |
| North-East | 392 |
Brookfield Partners perspective. Real supply for a tenant is vacancy plus subleases plus space released within twelve months. Vacancy and subleases alone total around 348,000 sqm, 7.6% more than official availability.
Submarkets: Śródmieście at 6.06%, North-West at 36.02%
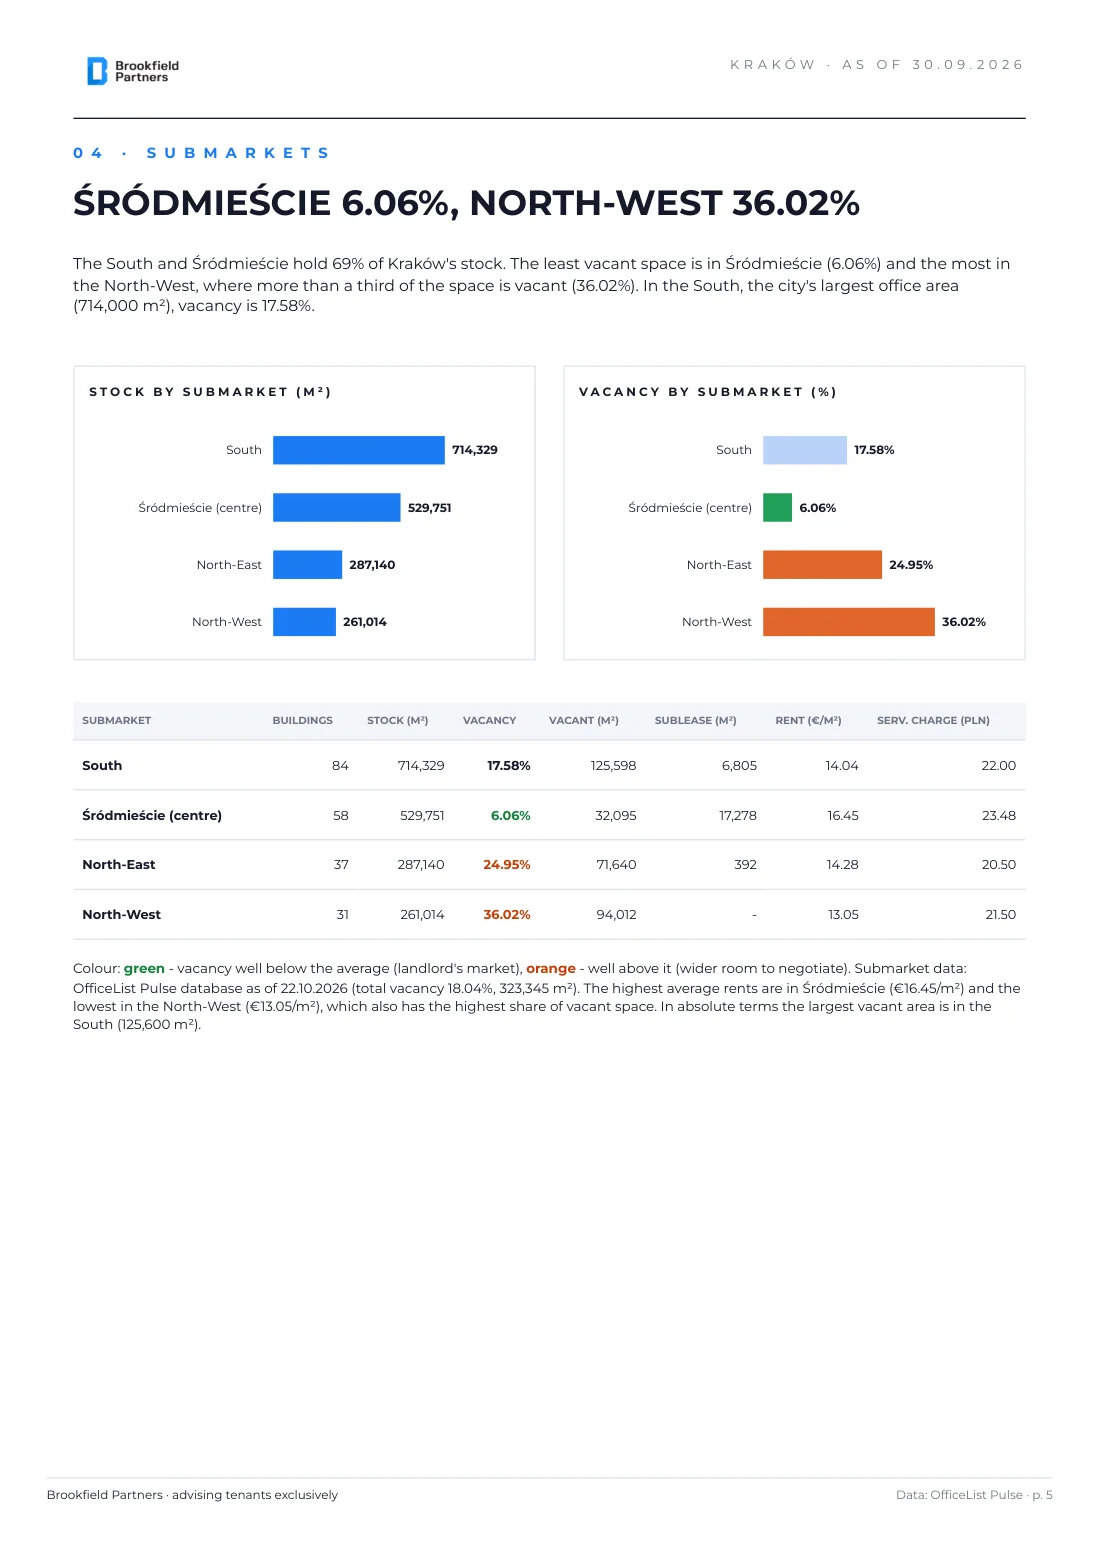
The South and Śródmieście hold 69% of Kraków's stock. The least vacant space is in Śródmieście (6.06%), now a landlord's market. In the North-West more than a third of the space is vacant (36.02%) and in the North-East one metre in four (24.95%), with rents €2.2-3.4/sqm lower than in the centre. In the South, the city's largest office area with 714,000 sqm of stock, vacancy is 17.58%, and in absolute terms this is where most vacant space is (125,600 sqm).
Kraków office market by submarket (database as of 22.10.2026)
| Submarket | Buildings | Stock (sqm) | Vacancy | Vacant (sqm) | Sublease (sqm) | Rent (€/sqm) | Serv. charge (PLN) |
|---|
| South | 84 | 714,329 | 17.58% | 125,598 | 6,805 | 14.04 | 22.00 |
| Śródmieście | 58 | 529,751 | 6.06% | 32,095 | 17,278 | 16.45 | 23.48 |
| North-East | 37 | 287,140 | 24.95% | 71,640 | 392 | 14.28 | 20.50 |
| North-West | 31 | 261,014 | 36.02% | 94,012 | - | 13.05 | 21.50 |
Rent is the average asking rate for available space; the service charge is the median of quoted advances. Submarket data reflect the database as of 22 October 2026 (total vacancy 18.04%, 323,345 sqm).
Supply: 55,000 sqm under construction, 3.1% of stock
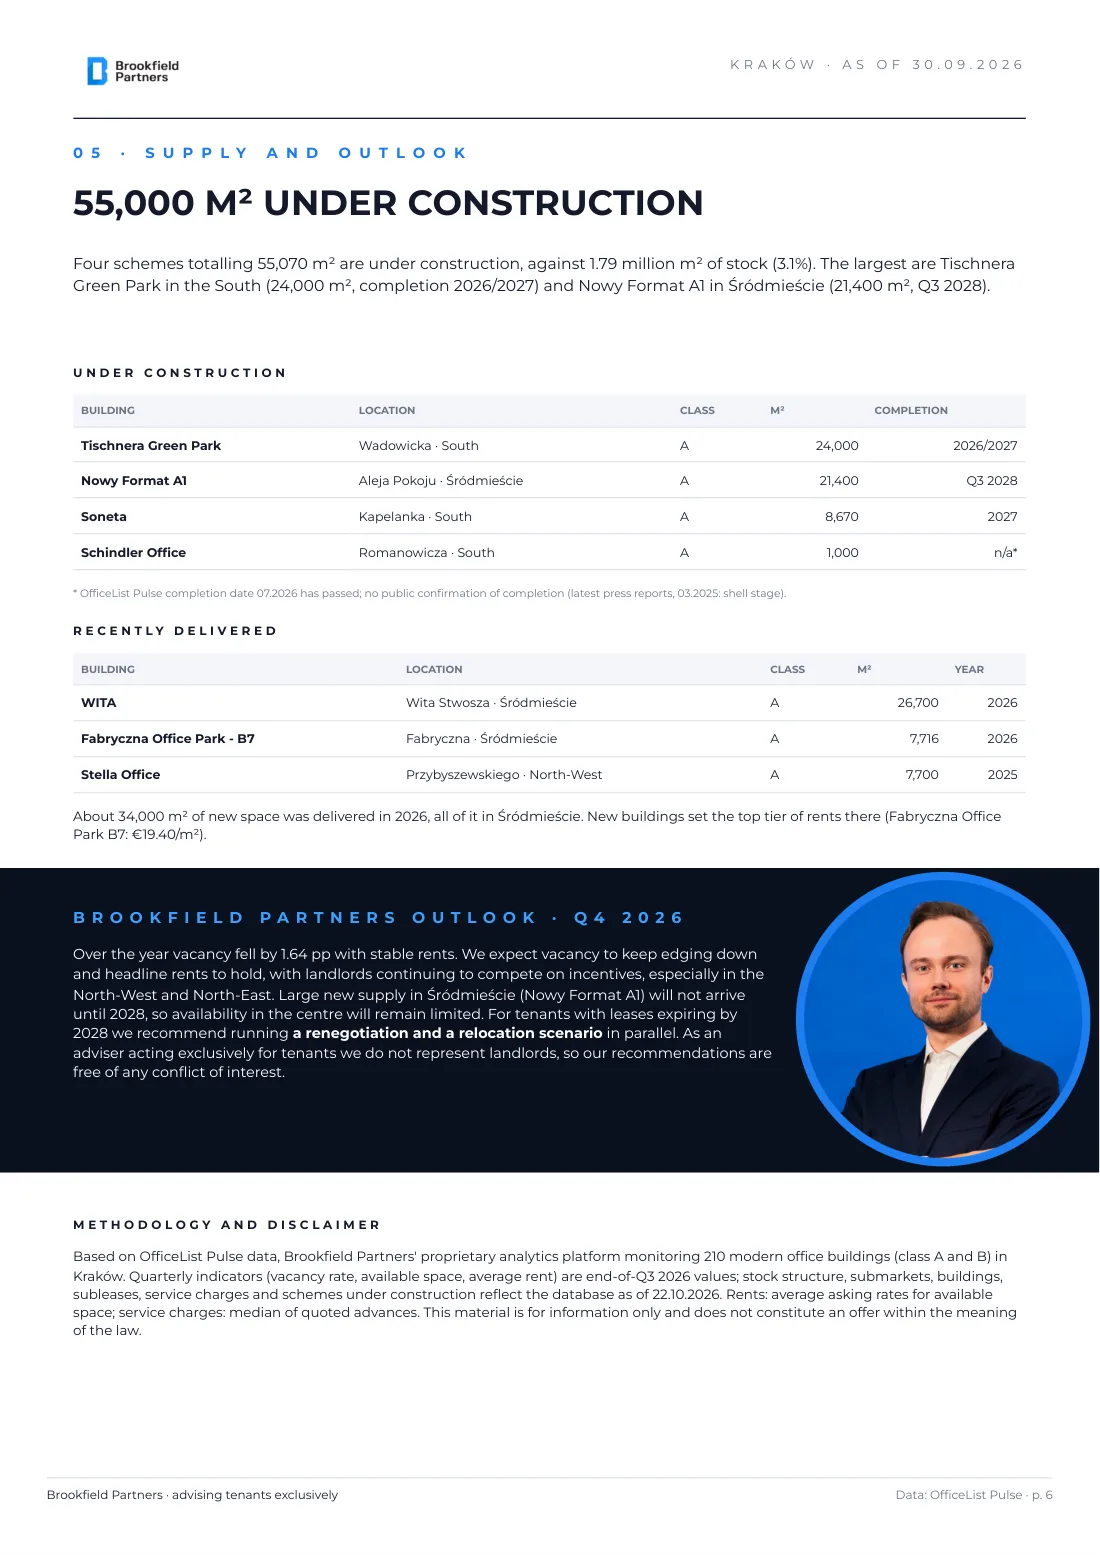
Four schemes totalling 55,070 sqm are under construction, against 1.79 million sqm of stock. The largest are Tischnera Green Park in the South (24,000 sqm, completion 2026/2027) and Nowy Format A1 in Śródmieście (21,400 sqm, Q3 2028). About 34,000 sqm was delivered in 2026, all of it in Śródmieście: WITA (26,700 sqm) and Fabryczna Office Park B7 (7,716 sqm). New buildings set the top tier of rents there, with B7 quoting €19.40/sqm.
Under construction
| Building | Location | Class | sqm | Completion |
|---|
| Tischnera Green Park | Wadowicka · South | A | 24,000 | 2026/2027 |
| Nowy Format A1 | Aleja Pokoju · Śródmieście | A | 21,400 | Q3 2028 |
| Soneta | Kapelanka · South | A | 8,670 | 2027 |
| Schindler Office | Romanowicza · South | A | 1,000 | n/a* |
* The OfficeList Pulse database gives a completion date of 07.2026 for Schindler Office, which has passed. There is no public confirmation of completion; the latest press reports, from March 2025, described the building at shell stage.
Recently delivered
| Building | Location | Class | sqm | Year |
|---|
| WITA | Wita Stwosza · Śródmieście | A | 26,700 | 2026 |
| Fabryczna Office Park - B7 | Fabryczna · Śródmieście | A | 7,716 | 2026 |
| Stella Office | Przybyszewskiego · North-West | A | 7,700 | 2025 |
Brookfield Partners outlook for Q4 2026. Over the year vacancy fell by 1.64 pp with stable rents. We expect vacancy to keep edging down and headline rents to hold, with landlords continuing to compete on incentives, especially in the North-West and North-East. Large new supply in Śródmieście (Nowy Format A1) will not arrive until 2028, so availability in the centre will remain limited. For tenants with leases expiring by 2028 we recommend running a renegotiation and a relocation scenario in parallel. As an adviser acting exclusively for tenants we do not represent landlords, so our recommendations are free of any conflict of interest.
Methodology
The report is based on OfficeList Pulse data, Brookfield Partners' proprietary analytics platform monitoring 210 modern office buildings in Kraków (117 class A and 93 class B). Quarterly indicators (vacancy rate, available space, average rent) are end-of-Q3 2026 values. Stock structure, submarkets, buildings, subleases, service charges and schemes under construction reflect the database as of 22 October 2026. Rents are average asking rates for available space; service charges are the median of quoted advances. This material is for information only and does not constitute an offer within the meaning of the law.