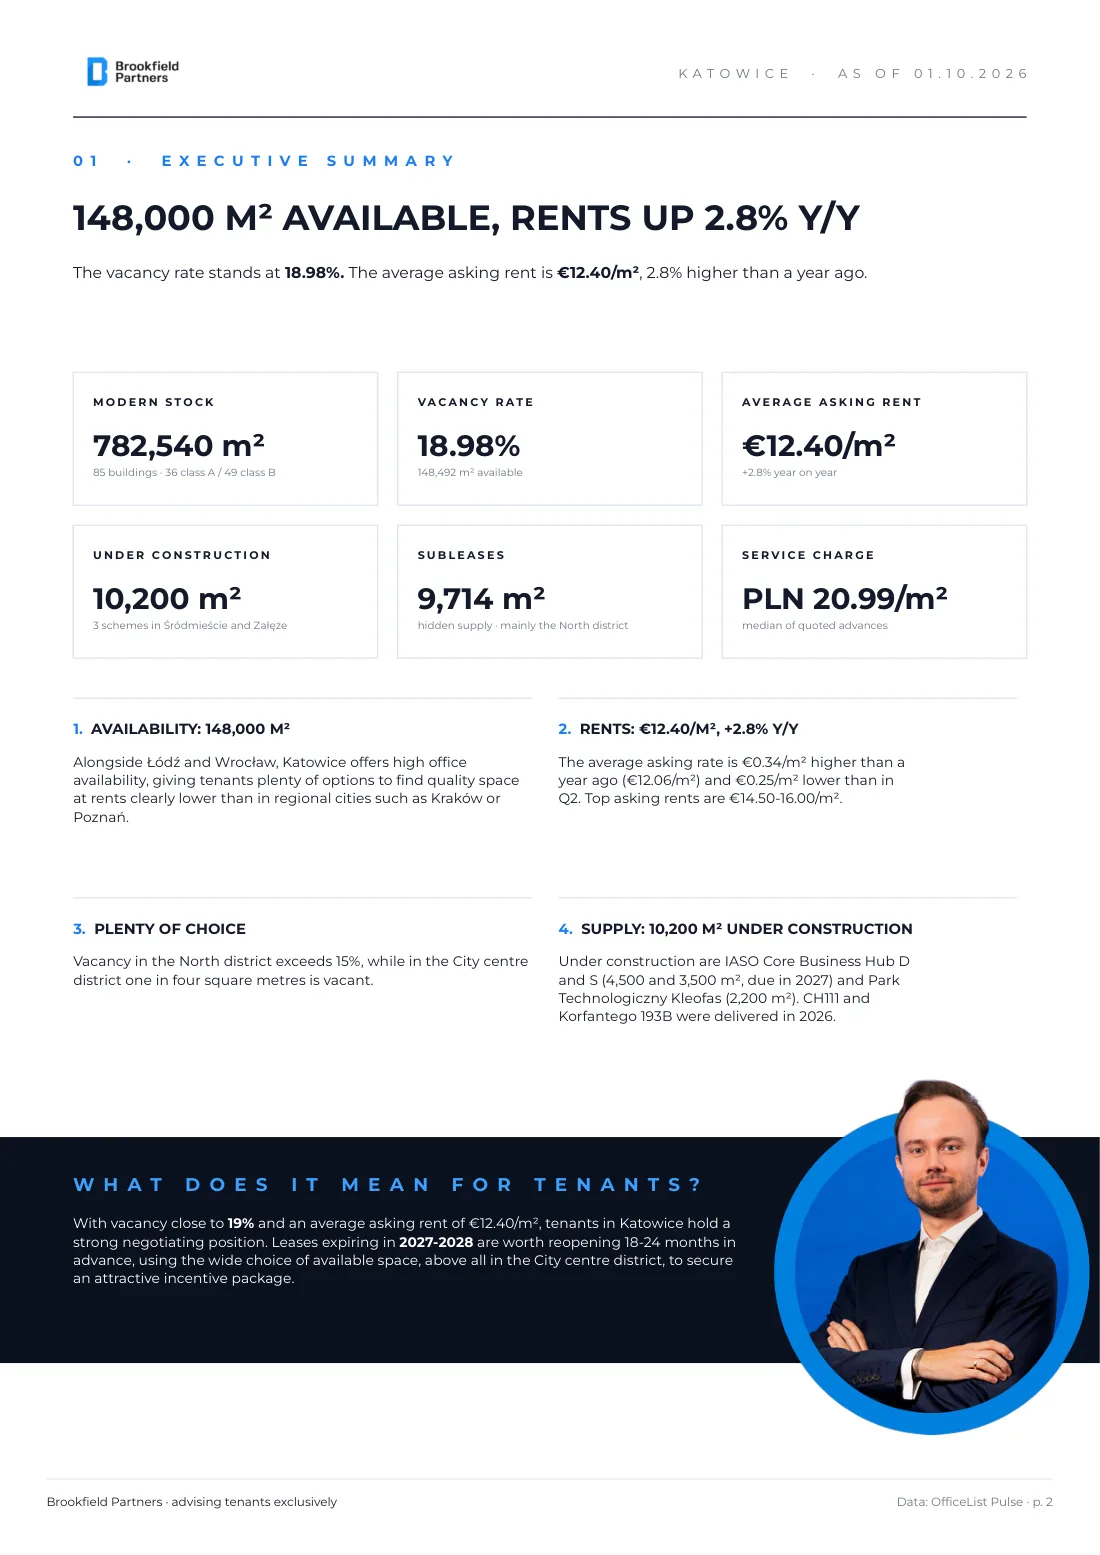
Rents: €12.40/sqm, up 2.8% year on year
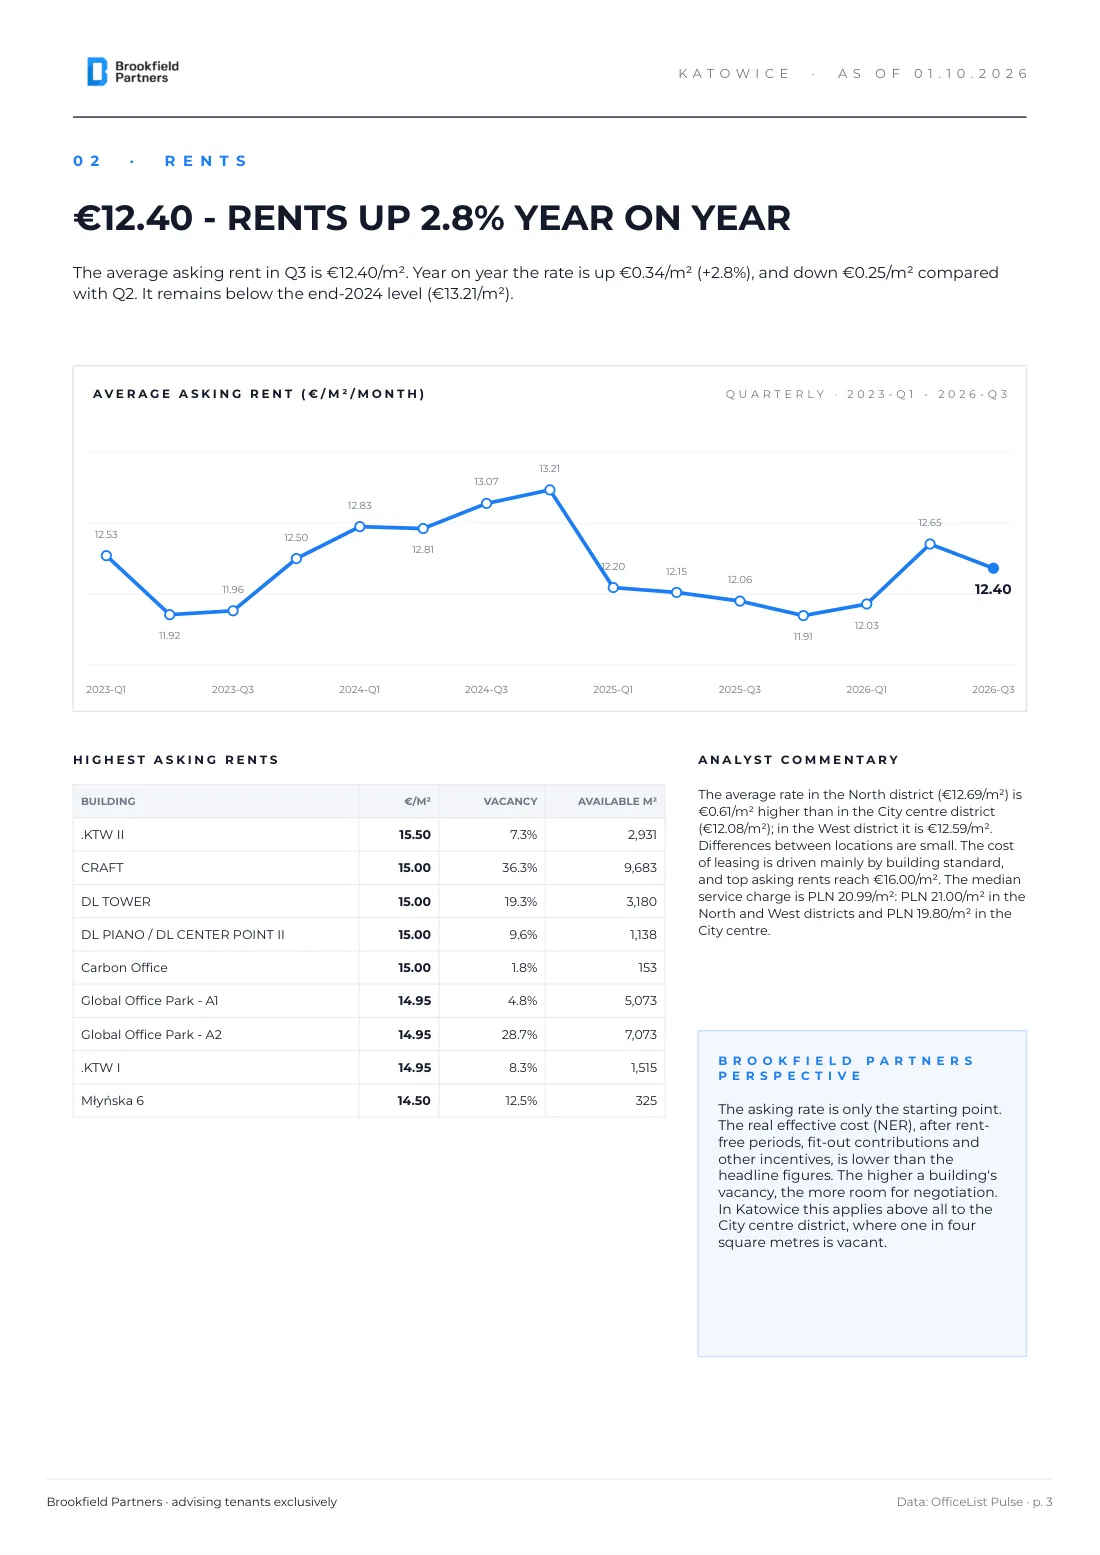
The average asking rent for available space in Q3 is €12.40/sqm. That is €0.34/sqm more than in Q3 2025 (€12.06/sqm) and €0.25/sqm less than in Q2 2026 (€12.65/sqm). The rate remains below its end-2024 level of €13.21/sqm, the highest in the series since 2023.
Average asking rent (€/sqm/month), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| €/sqm | 12.53 | 11.96 | 12.83 | 13.07 | 12.20 | 12.06 | 12.03 | 12.65 | 12.40 |
Highest asking rents
| Building | €/sqm | Vacancy | Available sqm |
|---|
| .KTW II | 15.50 | 7.3% | 2,931 |
| CRAFT | 15.00 | 36.3% | 9,683 |
| DL TOWER | 15.00 | 19.3% | 3,180 |
| DL PIANO / DL CENTER POINT II | 15.00 | 9.6% | 1,138 |
| Carbon Office | 15.00 | 1.8% | 153 |
| Global Office Park - A1 | 14.95 | 4.8% | 5,073 |
| Global Office Park - A2 | 14.95 | 28.7% | 7,073 |
| .KTW I | 14.95 | 8.3% | 1,515 |
| Młyńska 6 | 14.50 | 12.5% | 325 |
The average rate in the North district (€12.69/sqm) is €0.61/sqm higher than in the City centre district (€12.08/sqm), while in the West district it is €12.59/sqm. Differences between locations are small, and the cost of leasing is driven mainly by building standard. Top asking rents reach €16.00/sqm. The median quoted service charge advance is PLN 20.99/sqm: PLN 21.00/sqm in the North and West districts and PLN 19.80/sqm in the City centre. It has to be added to the rent in the lease budget.
Brookfield Partners perspective. The asking rent is only a starting point. The real effective cost (NER), after rent-free periods, fit-out contributions and other incentives, is lower than the headline figures. The higher a building's vacancy, the more room there is to negotiate. In Katowice this applies above all to the City centre district, where one in four square metres is vacant.
Vacancy and availability: 18.98%, or 148,000 sqm of vacant space
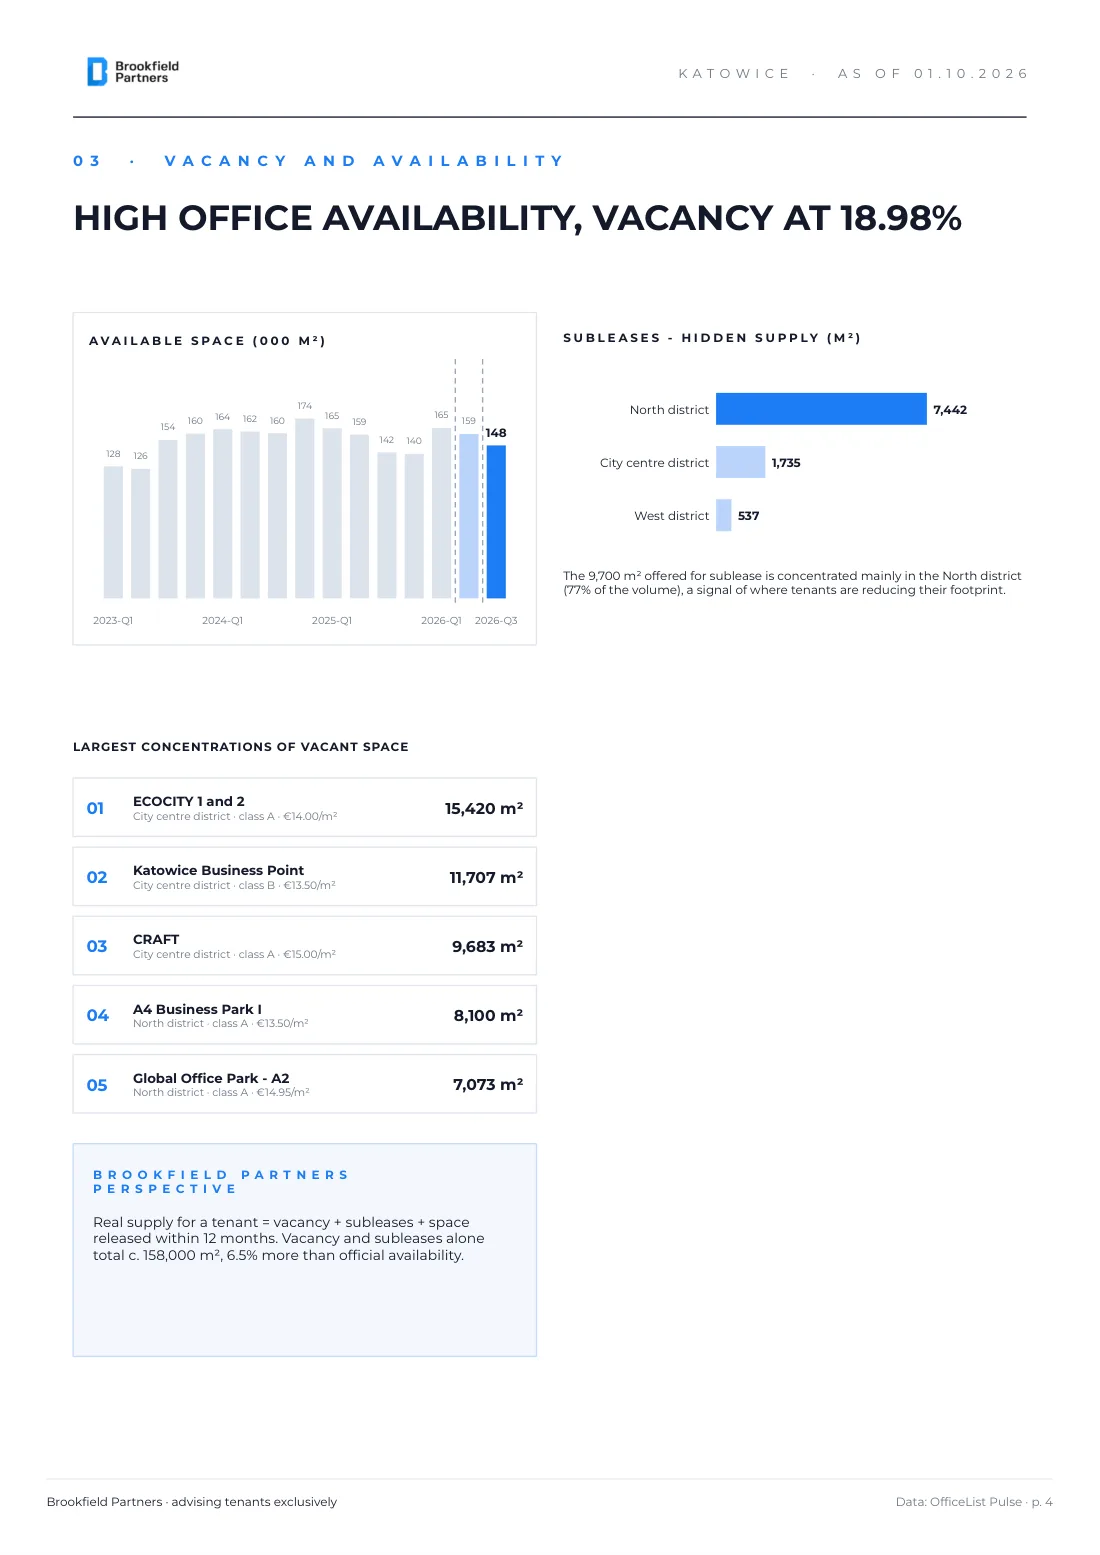
The vacancy rate in Katowice's modern office stock is 18.98%. Space available immediately totals 148,492 sqm, about 6,000 sqm more than a year ago (142,000 sqm) and 11,000 sqm less than in Q2 2026. Alongside Łódź and Wrocław, it is one of the regional markets with the highest office availability, and rents are clearly lower than in Kraków or Poznań.
Available space (000 sqm), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| Available (000 sqm) | 128 | 154 | 164 | 160 | 165 | 142 | 165 | 159 | 148 |
Largest concentrations of vacant space
| Building | District | Class | Rent €/sqm | Vacant sqm |
|---|
| ECOCITY 1 and 2 | City centre | A | 14.00 | 15,420 |
| Katowice Business Point | City centre | B | 13.50 | 11,707 |
| CRAFT | City centre | A | 15.00 | 9,683 |
| A4 Business Park I | North | A | 13.50 | 8,100 |
| Global Office Park - A2 | North | A | 14.95 | 7,073 |
Three of the five largest blocks of vacant space are in the City centre district. Sublease space totals 9,714 sqm, 77% of it in the North district (7,442 sqm). It shows where tenants are reducing their footprint, and for those looking for an office a sublease is often the quickest route to a ready, fitted-out space.
Subleases - hidden supply by district (sqm)
| District | sqm |
|---|
| North district | 7,442 |
| City centre district | 1,735 |
| West district | 537 |
Brookfield Partners perspective. Real supply for a tenant is vacancy plus subleases plus space released within twelve months. Vacancy and subleases alone total around 158,000 sqm, 6.5% more than official availability.
Districts: City centre at 25.85%, West at 4.41%
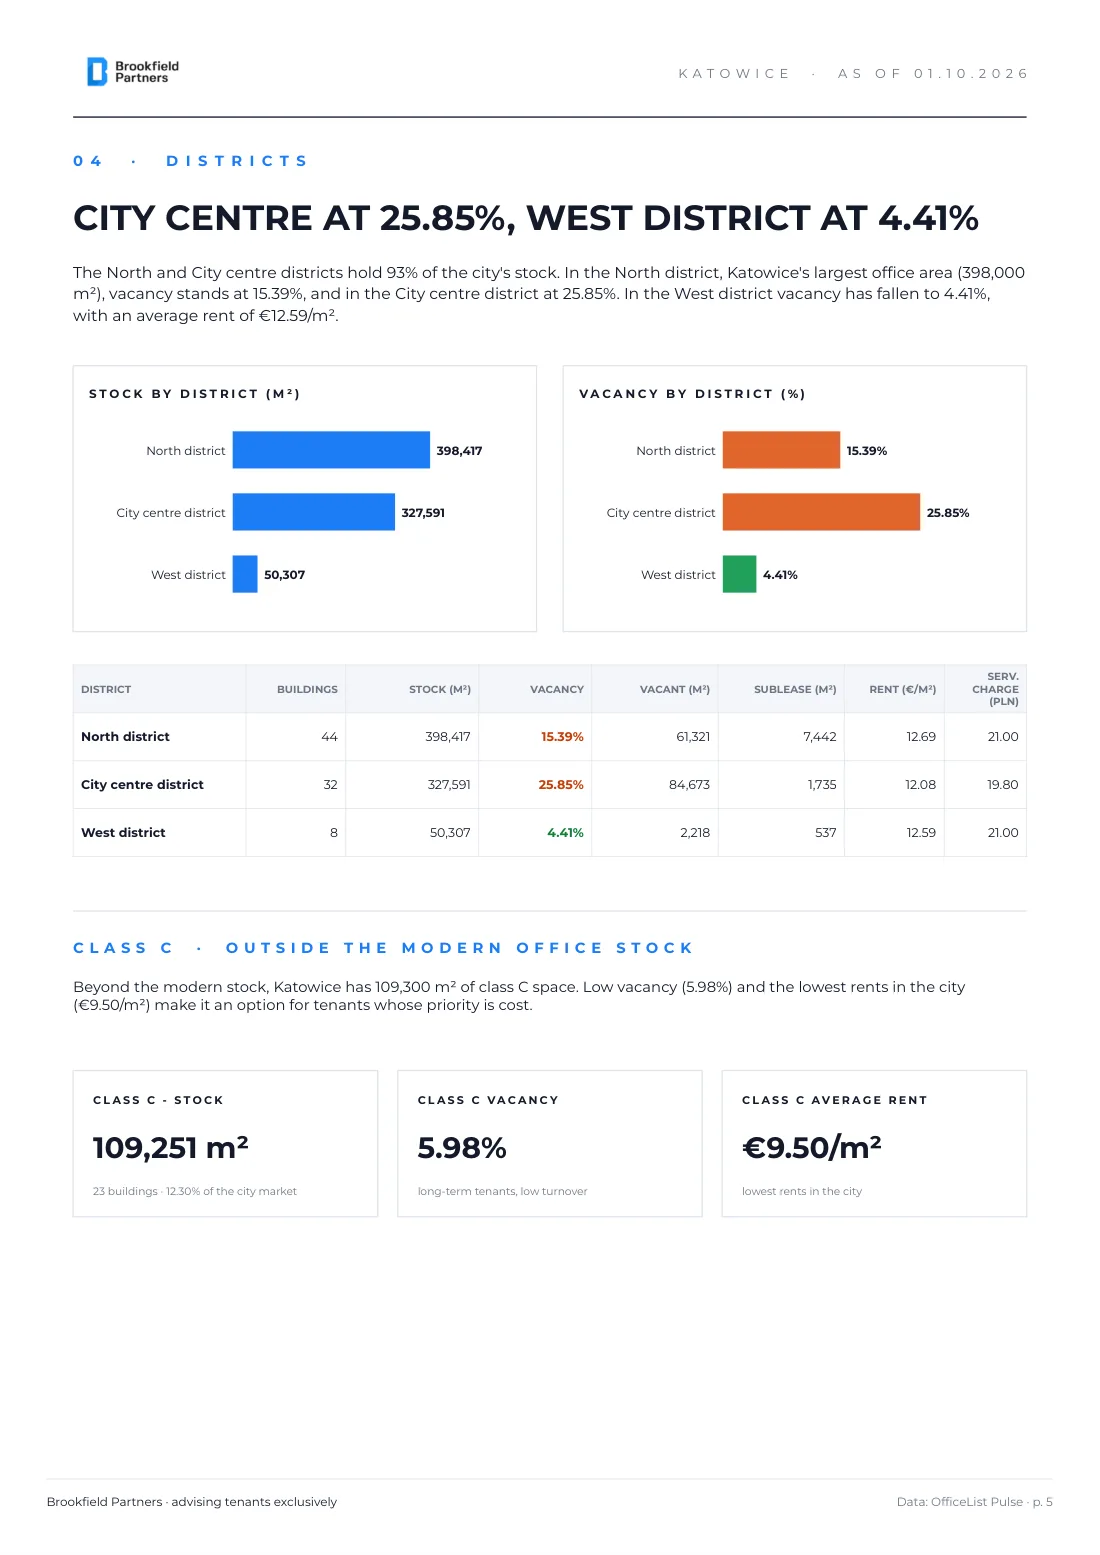
The North and City centre districts hold 93% of the city's stock. In the North district, Katowice's largest office area (398,000 sqm), vacancy is 15.39%, and in the City centre district 25.85%. The City centre accounts for 84,700 sqm of vacant space, or 57% of all availability in the city. The tightest is the West district, where vacancy has fallen to 4.41% and the average rent is €12.59/sqm.
Katowice office market by district (as of 01.10.2026)
| District | Buildings | Stock (sqm) | Vacancy | Vacant (sqm) | Sublease (sqm) | Rent (€/sqm) | Serv. charge (PLN) |
|---|
| North district | 44 | 398,417 | 15.39% | 61,321 | 7,442 | 12.69 | 21.00 |
| City centre district | 32 | 327,591 | 25.85% | 84,673 | 1,735 | 12.08 | 19.80 |
| West district | 8 | 50,307 | 4.41% | 2,218 | 537 | 12.59 | 21.00 |
Rent is the average asking rate for available space; the service charge is the median of quoted advances. Beyond the three districts, the stock includes one more building in Szopienice-Burowiec (6,225 sqm, 4.5% vacancy).
Class C outside the modern stock
Beyond the modern stock, Katowice has 109,300 sqm of class C space in 23 buildings, or 12.30% of the city's office market. Vacancy here is 5.98%, as the buildings are occupied mainly by long-term tenants, and the average rent (€9.50/sqm) is the lowest in the city. It is an option for tenants whose priority is cost.
Supply: 10,200 sqm under construction in three schemes
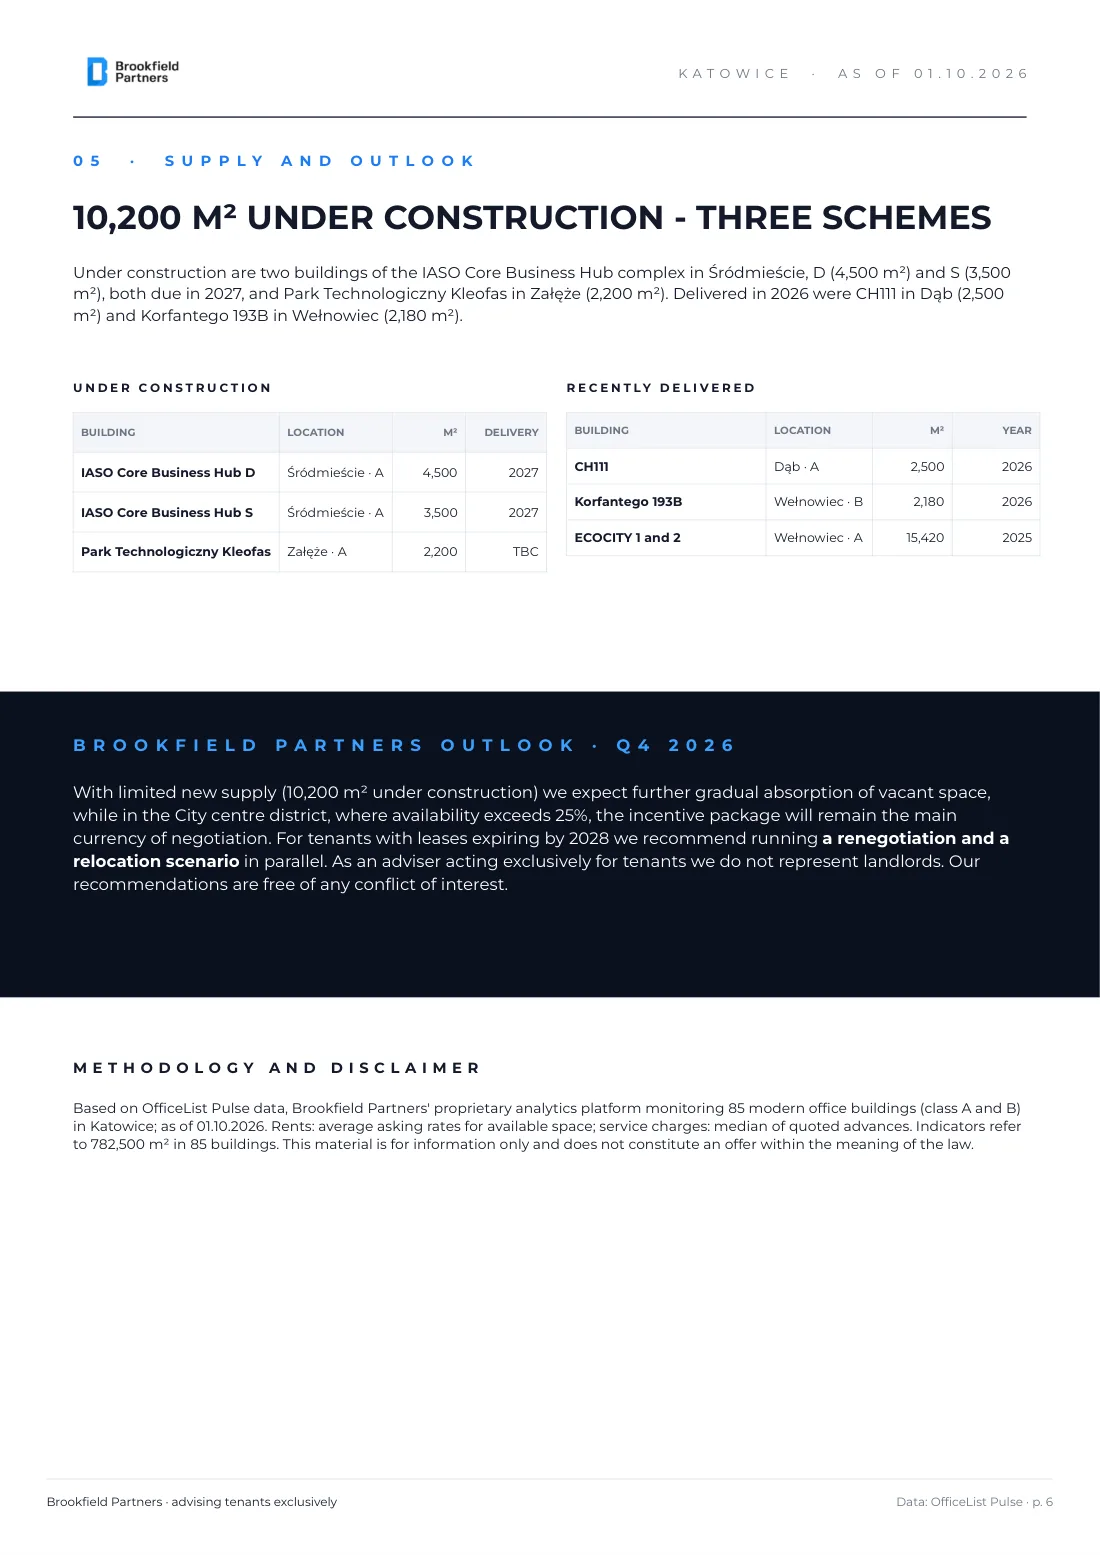
Under construction are two buildings of the IASO Core Business Hub complex in Śródmieście, D (4,500 sqm) and S (3,500 sqm), both due in 2027, and Park Technologiczny Kleofas in Załęże (2,200 sqm), whose completion date is not yet confirmed. New supply equals 1.3% of the existing stock. Delivered in 2026 were CH111 in Dąb (2,500 sqm) and Korfantego 193B in Wełnowiec (2,180 sqm).
Under construction
| Building | Location | Class | sqm | Completion |
|---|
| IASO Core Business Hub D | Śródmieście | A | 4,500 | 2027 |
| IASO Core Business Hub S | Śródmieście | A | 3,500 | 2027 |
| Park Technologiczny Kleofas | Załęże | A | 2,200 | TBC |
Recently delivered
| Building | Location | Class | sqm | Year |
|---|
| CH111 | Dąb | A | 2,500 | 2026 |
| Korfantego 193B | Wełnowiec | B | 2,180 | 2026 |
| ECOCITY 1 and 2 | Wełnowiec | A | 15,420 | 2025 |
Brookfield Partners outlook for Q4 2026. With limited new supply we expect further gradual absorption of vacant space. In the City centre district, where availability exceeds 25%, the incentive package will remain the main currency of negotiation. For tenants with leases expiring by 2028 we recommend running a renegotiation and a relocation scenario in parallel. As an adviser acting exclusively for tenants we do not represent landlords, so our recommendations are free of any conflict of interest.
Methodology
The report is based on OfficeList Pulse data, Brookfield Partners' proprietary analytics platform monitoring 85 modern office buildings in Katowice (36 class A and 49 class B, 782,500 sqm in total), as of 1 October 2026. Rents are average asking rates for available space; service charges are the median of quoted advances. This material is for information only and does not constitute an offer within the meaning of the law.