Rents: €12.44/sqm, €1.37 more than at the start of 2023
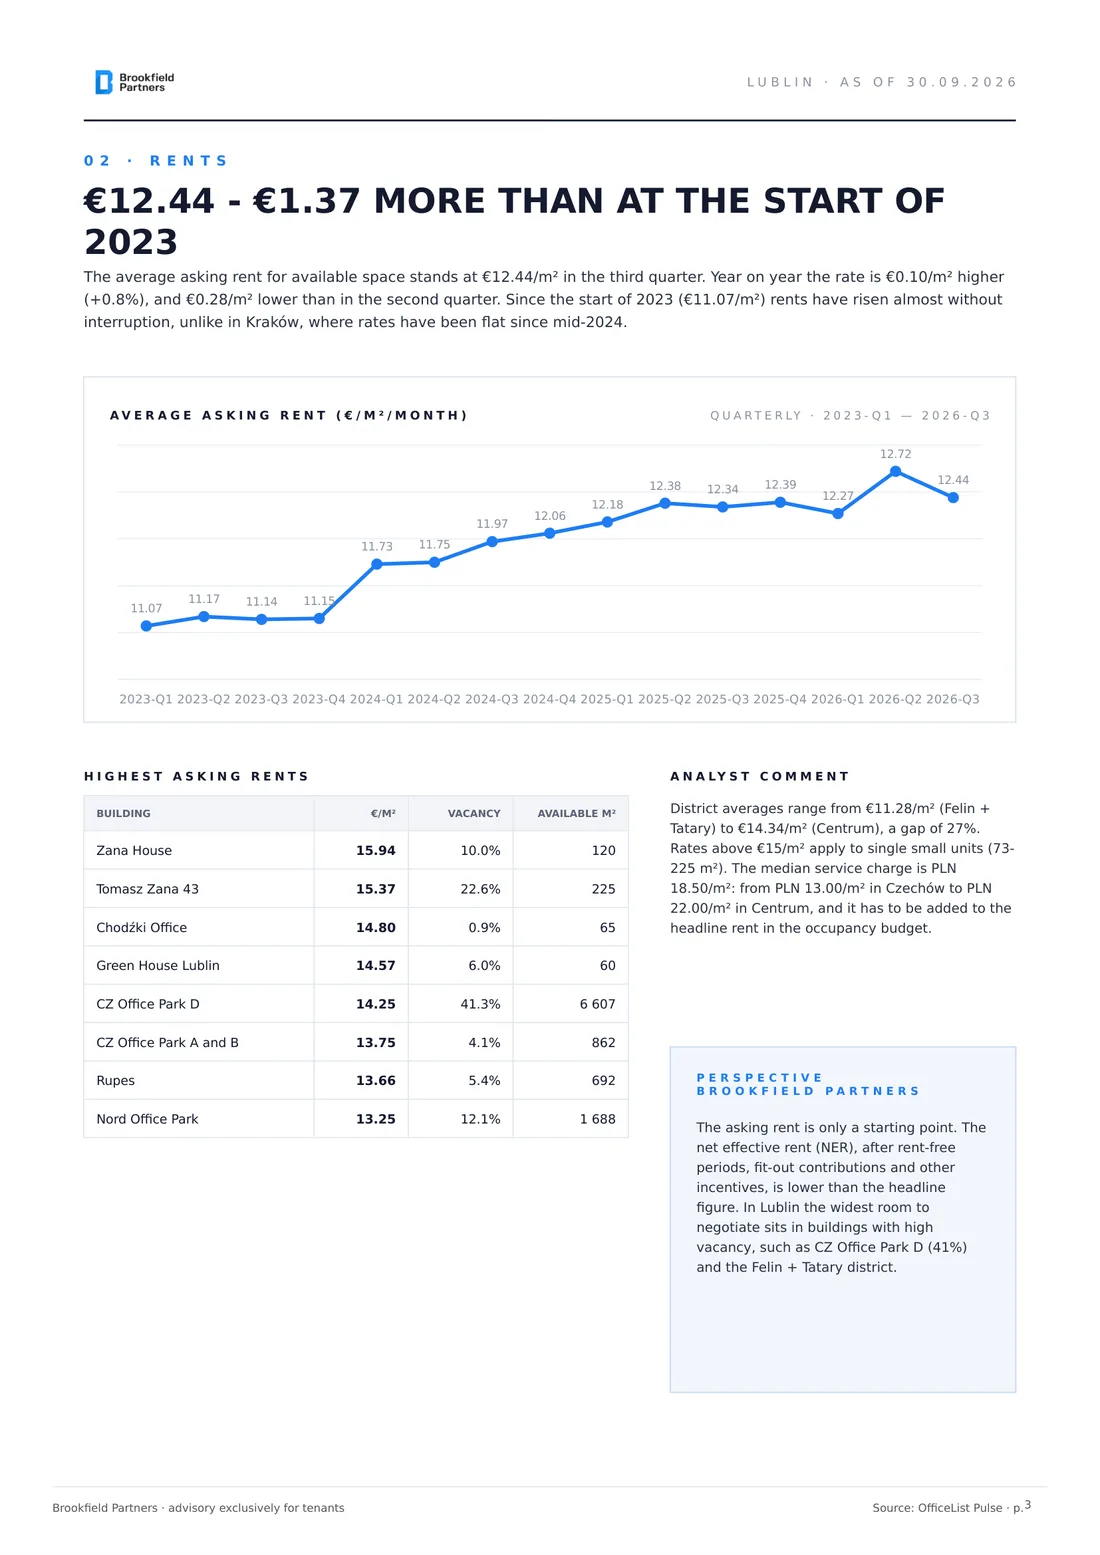
The average asking rent for available space stands at €12.44/sqm in the third quarter. Year on year the rate is €0.10/sqm higher, up 0.8%, and €0.28/sqm lower than in the second quarter. Since the start of 2023, when it stood at €11.07/sqm, rents in Lublin have risen almost without interruption, unlike in Kraków, where rates have been flat since mid-2024.
Average asking rent (€/sqm/month), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| €/sqm | 11.07 | 11.14 | 11.73 | 11.97 | 12.18 | 12.34 | 12.27 | 12.72 | 12.44 |
Highest asking rents
| Building | €/sqm | Vacancy | Available sqm |
|---|
| Zana House | 15.94 | 10.0% | 120 |
| Tomasz Zana 43 | 15.37 | 22.6% | 225 |
| Chodźki Office | 14.80 | 0.9% | 65 |
| Green House Lublin | 14.57 | 6.0% | 60 |
| CZ Office Park D | 14.25 | 41.3% | 6,607 |
| CZ Office Park A i B | 13.75 | 4.1% | 862 |
| Rupes | 13.66 | 5.4% | 692 |
| Nord Office Park | 13.25 | 12.1% | 1,688 |
District averages range from €11.28/sqm in Felin + Tatary to €14.34/sqm in Centrum, a gap of 27%. Rates above €15/sqm apply to single small units of 73 to 225 sqm. The median quoted service charge advance is PLN 18.50/sqm, from PLN 13.00/sqm in Czechów to PLN 22.00/sqm in Centrum, and it has to be added to the headline rent in any occupancy budget.
Brookfield Partners perspective. The asking rent is only a starting point. The net effective rent, once rent-free periods, fit-out contributions and other incentives are taken into account, is lower than the headline figure. In Lublin the widest room to negotiate sits in buildings with high vacancy, such as CZ Office Park D at 41%, and in the Felin + Tatary district.
Vacancy and availability: 26,700 sqm, 40% less than in 2023
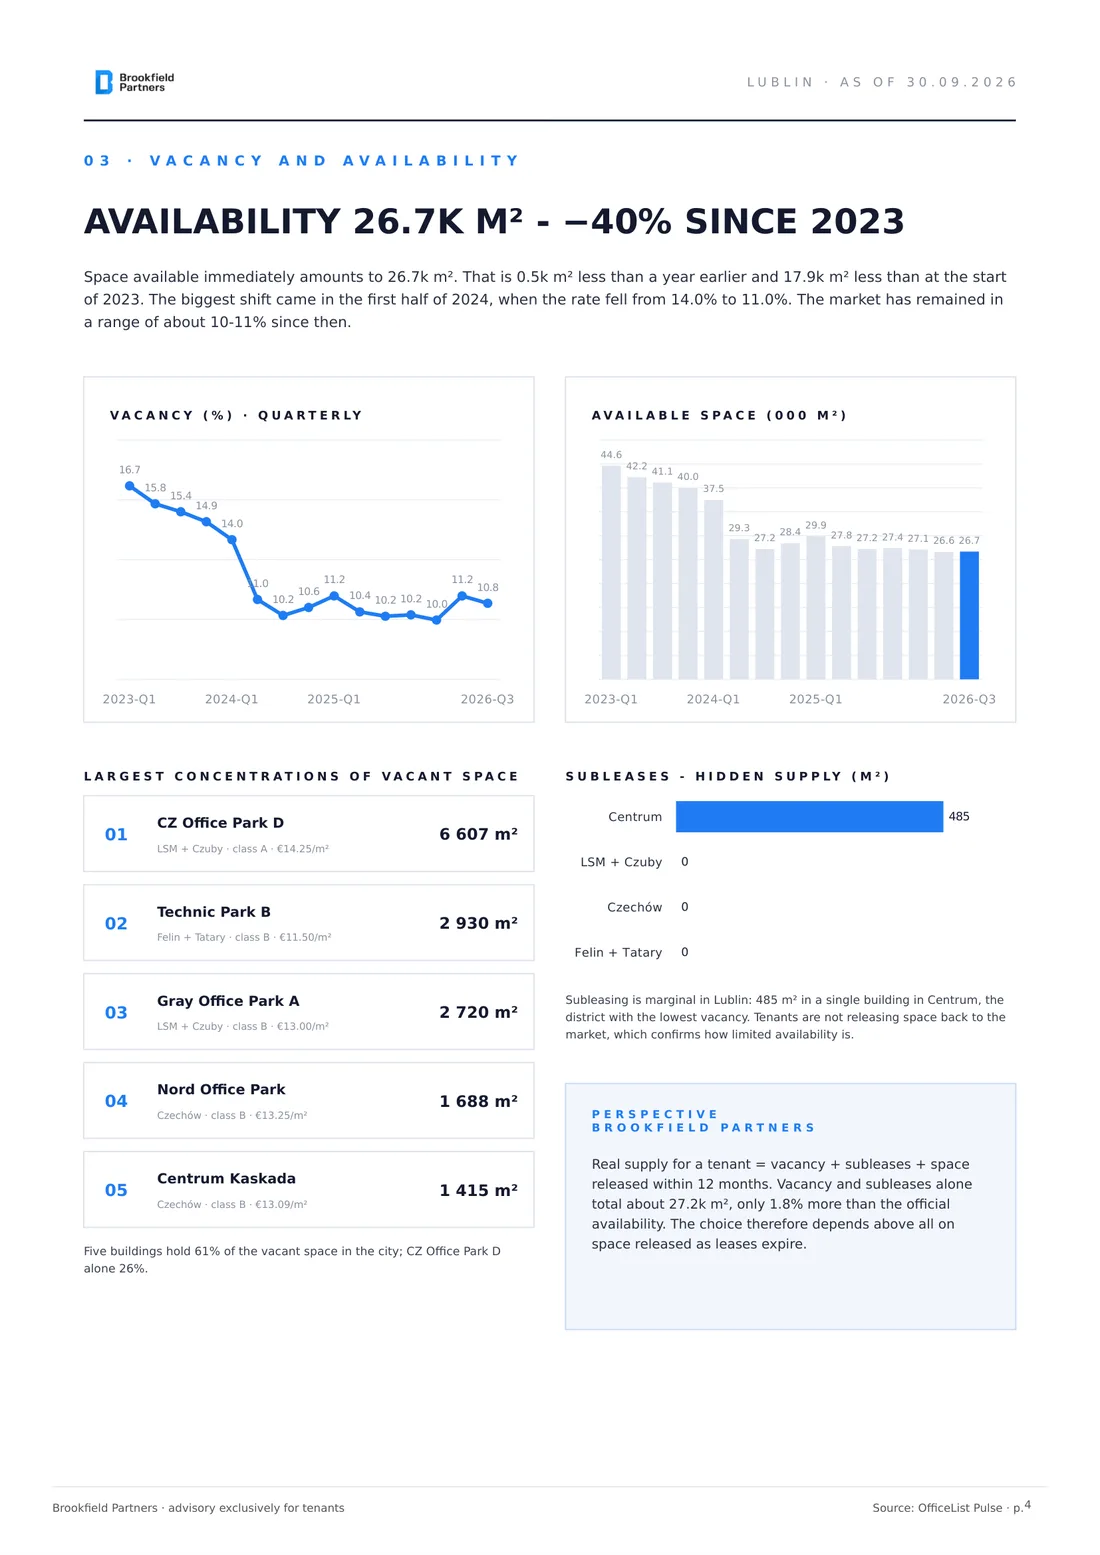
Space available immediately amounts to 26,700 sqm. That is 500 sqm less than a year earlier and 17,900 sqm less than at the start of 2023, when 44,600 sqm stood vacant. The biggest shift came in the first half of 2024, when the vacancy rate fell from 14.0% to 11.0%. The market has stayed in a range of roughly 10-11% since then.
Vacancy rate and available space, quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| Vacancy | 16.7% | 15.4% | 14.0% | 10.2% | 11.2% | 10.2% | 10.0% | 11.2% | 10.8% |
| Available (000 sqm) | 44.6 | 41.1 | 37.5 | 27.2 | 29.9 | 27.2 | 27.1 | 26.6 | 26.7 |
Largest concentrations of vacant space
| Building | District | Class | Rent €/sqm | Vacant sqm |
|---|
| CZ Office Park D | LSM + Czuby | A | 14.25 | 6,607 |
| Technic Park B | Felin + Tatary | B | 11.50 | 2,930 |
| Gray Office Park A | LSM + Czuby | B | 13.00 | 2,720 |
| Nord Office Park | Czechów | B | 13.25 | 1,688 |
| Centrum Kaskada | Czechów | B | 13.09 | 1,415 |
Five buildings hold 61% of the vacant space in the city, with CZ Office Park D alone accounting for 26%. That matters for a tenant looking for a larger unit, because only three buildings currently offer more than 2,500 sqm.
Subleases - hidden supply by district (sqm)
| District | sqm |
|---|
| Centrum | 485 |
| LSM + Czuby | 0 |
| Czechów | 0 |
| Felin + Tatary | 0 |
Subleasing is marginal in Lublin: 485 sqm in a single building in Centrum, the district with the lowest vacancy. Tenants are not releasing space back to the market, which further confirms how limited availability is.
Brookfield Partners perspective. Real supply for a tenant is vacancy plus subleases plus space announced for release within twelve months. Vacancy and subleases alone total around 27,200 sqm, only 1.8% more than the official availability figure. The choice therefore depends above all on space released as leases expire.
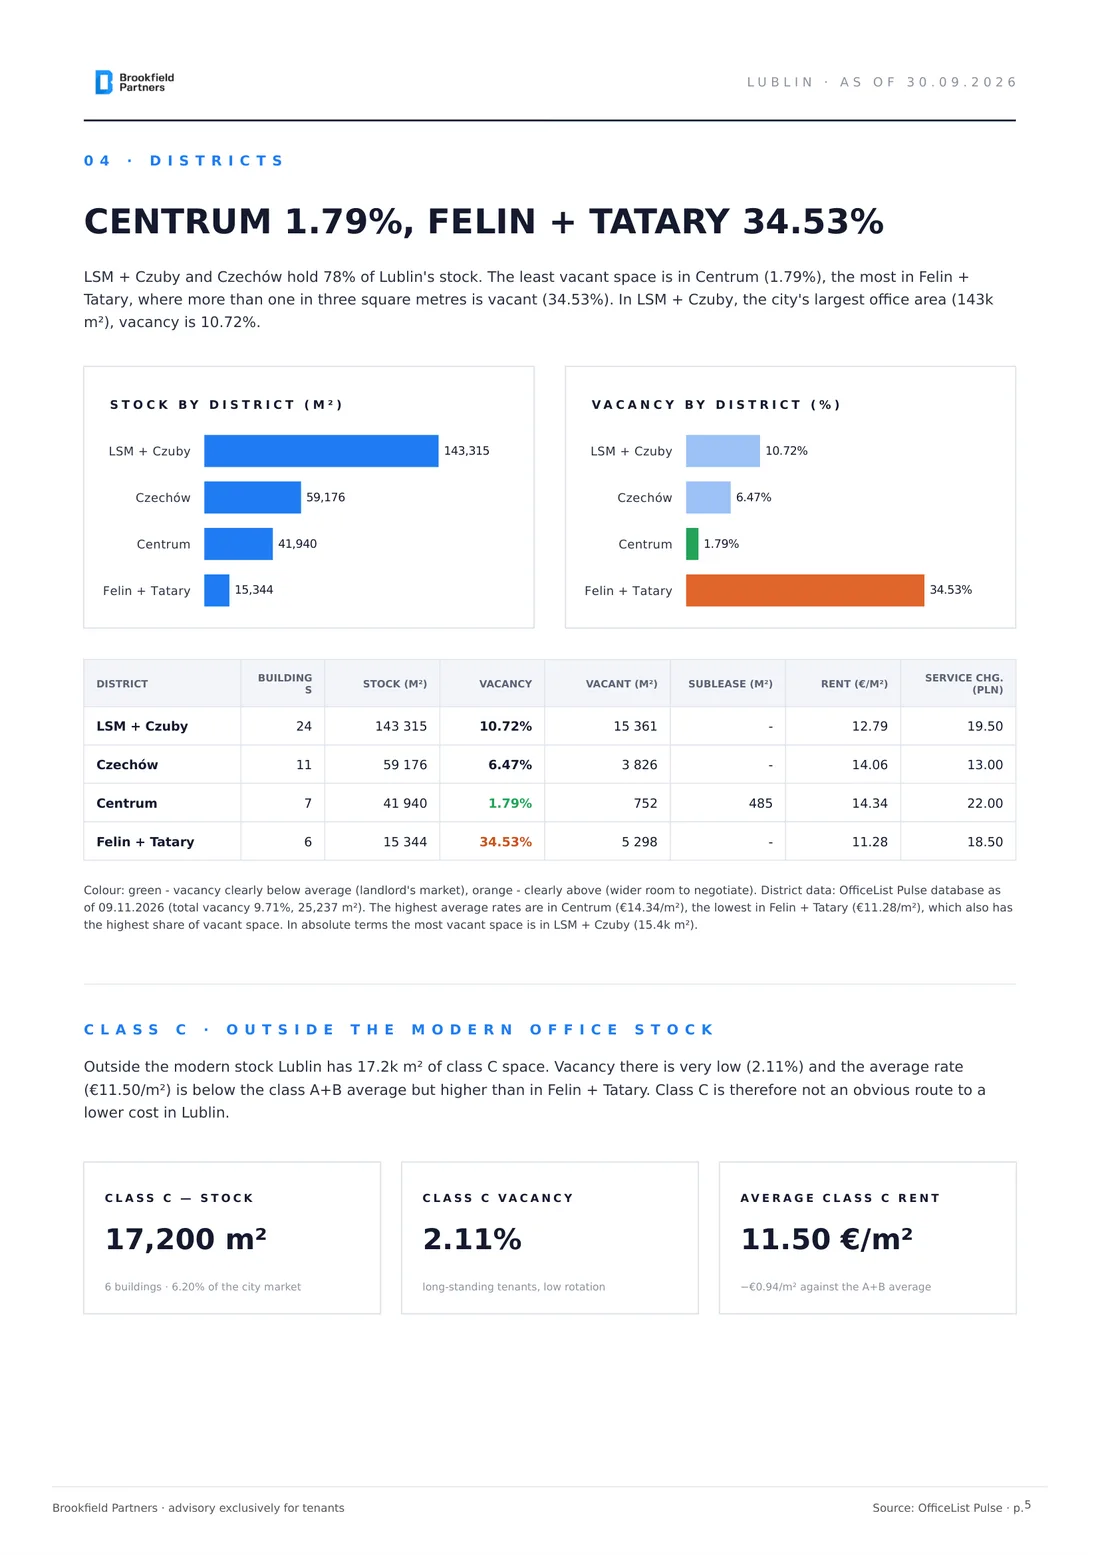
Districts: Centrum at 1.79%, Felin + Tatary at 34.53%
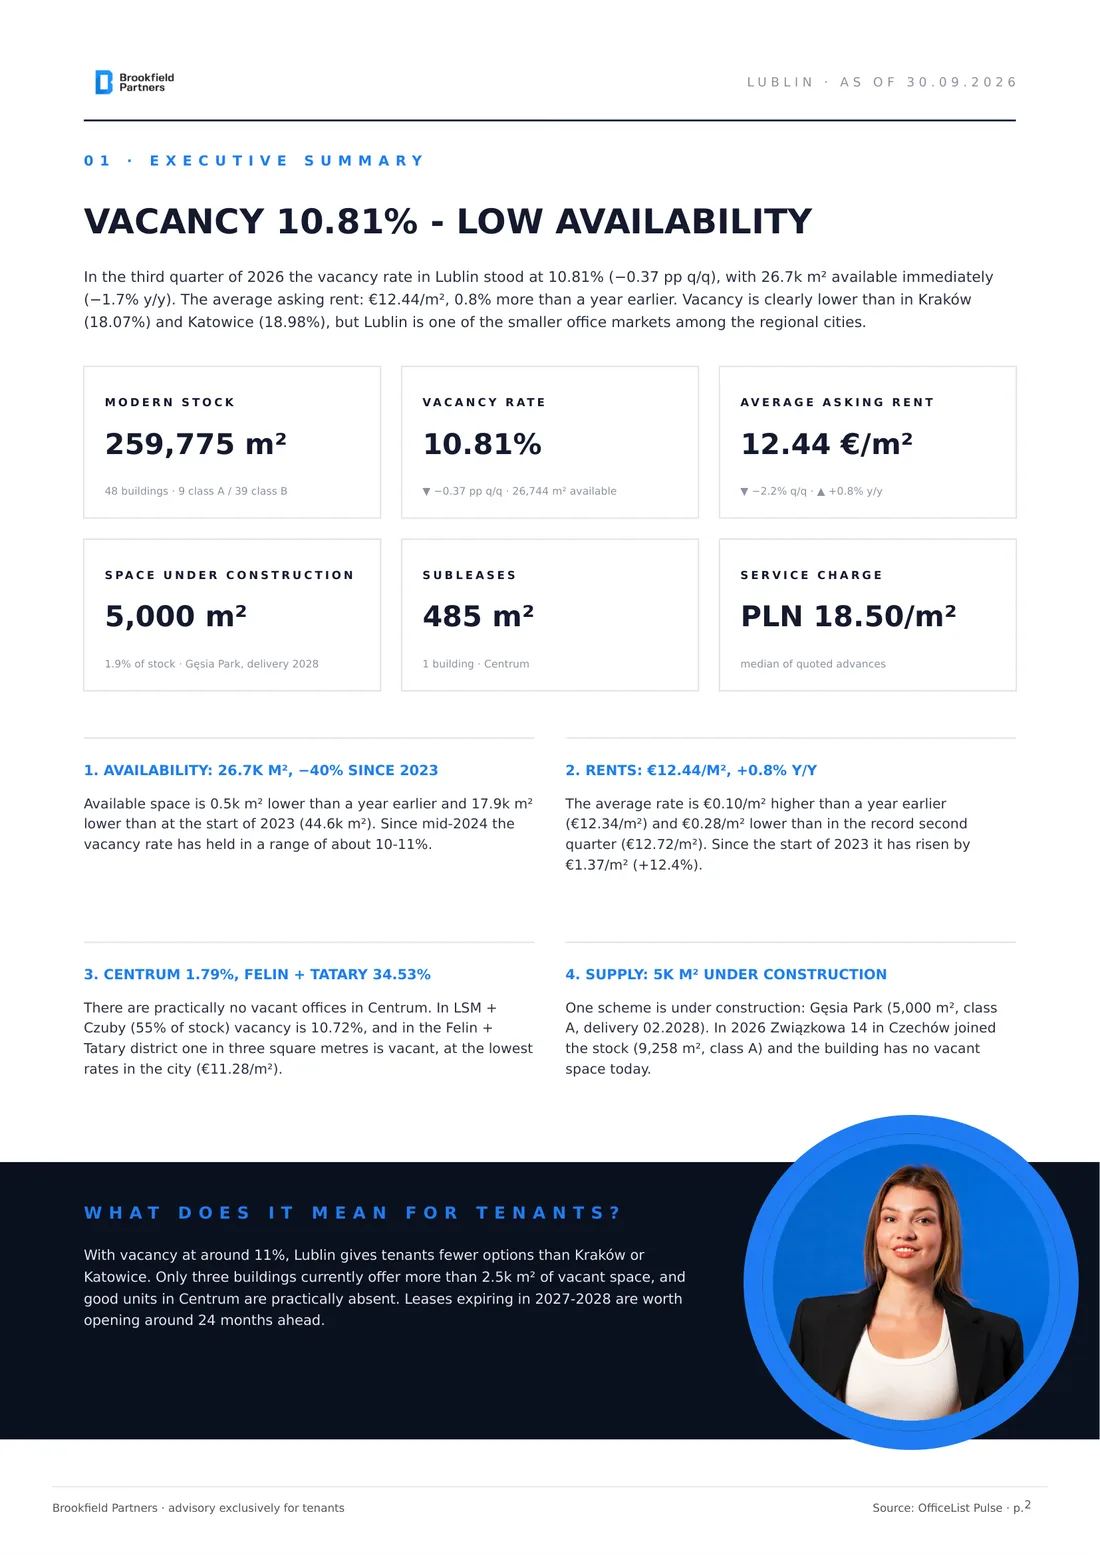
LSM + Czuby and Czechów hold 78% of Lublin's stock. The least vacant space sits in Centrum at 1.79%, and the most in Felin + Tatary, where more than one in three square metres is vacant. In LSM + Czuby, the city's largest office area with 143,000 sqm, vacancy reaches 10.72%.
Lublin office market by district
| District | Buildings | Stock (sqm) | Vacancy | Vacant (sqm) | Sublease (sqm) | Rent (€/sqm) | Service charge (PLN) |
|---|
| LSM + Czuby | 24 | 143,315 | 10.72% | 15,361 | - | 12.79 | 19.50 |
| Czechów | 11 | 59,176 | 6.47% | 3,826 | - | 14.06 | 13.00 |
| Centrum | 7 | 41,940 | 1.79% | 752 | 485 | 14.34 | 22.00 |
| Felin + Tatary | 6 | 15,344 | 34.53% | 5,298 | - | 11.28 | 18.50 |
District data reflects the OfficeList Pulse database as of 9 November 2026, when citywide vacancy stood at 9.71%, or 25,237 sqm. Quarterly indicators in the other tables are given as at the end of the third quarter, hence the difference against the 26,744 sqm available on 30 September.
Outside the modern stock, Lublin has 17,200 sqm of class C space across six buildings, equal to 6.20% of the city market. Vacancy there is very low at 2.11%, because those buildings house long-standing tenants with little rotation. The average rate of €11.50/sqm is €0.94/sqm below the class A and B average but higher than in Felin + Tatary, so class C is not an obvious route to a lower cost in Lublin.
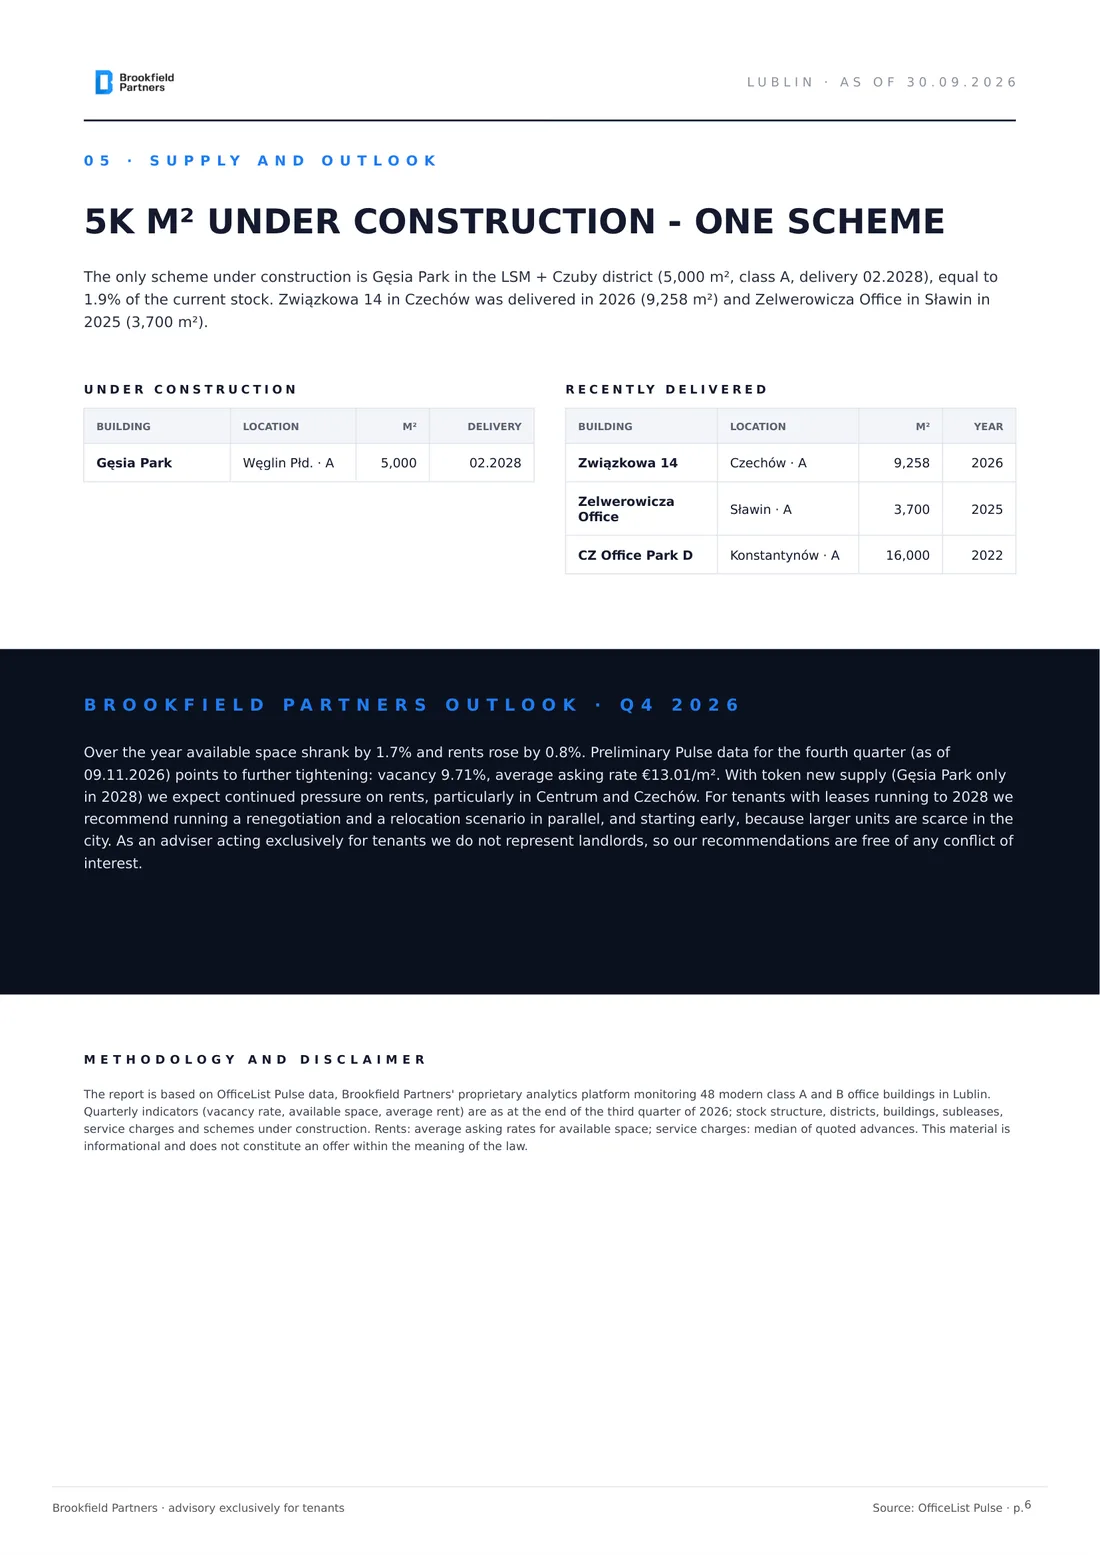
Supply and outlook: 5,000 sqm under construction in a single scheme
The only scheme under construction is Gęsia Park, 5,000 sqm of class A due for delivery in February 2028. That is 1.9% of the current stock. In 2026 Związkowa 14 in Czechów added 9,258 sqm and the building has no vacant space today. Zelwerowicza Office in Sławin was delivered in 2025.
Under construction
| Building | Location | Class | sqm | Delivery |
|---|
| Gęsia Park | Węglin Płd. | A | 5,000 | 02.2028 |
Recently delivered
| Building | Location | Class | sqm | Year |
|---|
| Związkowa 14 | Czechów | A | 9,258 | 2026 |
| Zelwerowicza Office | Sławin | A | 3,700 | 2025 |
| CZ Office Park D | Konstantynów | A | 16,000 | 2022 |
Brookfield Partners perspective for Q4 2026. Over the year available space shrank by 1.7% and rents rose by 0.8%. Preliminary Pulse data as of 9 November 2026 points to further tightening: vacancy at 9.71% and an average asking rate of €13.01/sqm. With token new supply, since Gęsia Park only arrives in 2028, we expect continued pressure on rents, particularly in Centrum and Czechów. For tenants with leases expiring by 2028 we recommend running a renegotiation and a relocation scenario in parallel, and starting early, because larger units are scarce in the city. As an adviser acting exclusively for tenants we do not represent landlords, so our recommendations are free of any conflict of interest.
Methodology
The report is based on OfficeList Pulse data, Brookfield Partners' proprietary analytics platform monitoring 48 modern class A and B office buildings in Lublin. Quarterly indicators, meaning the vacancy rate, available space and average rent, are given as at the end of the third quarter of 2026. Stock structure, districts, buildings, subleases, service charges and schemes under construction reflect the database as of 9 November 2026. Rents are average asking rates for available space and service charges are the median of quoted advances. This material is informational and does not constitute an offer within the meaning of the law.