Rents: €15.63/sqm, 11.2% higher than a year ago
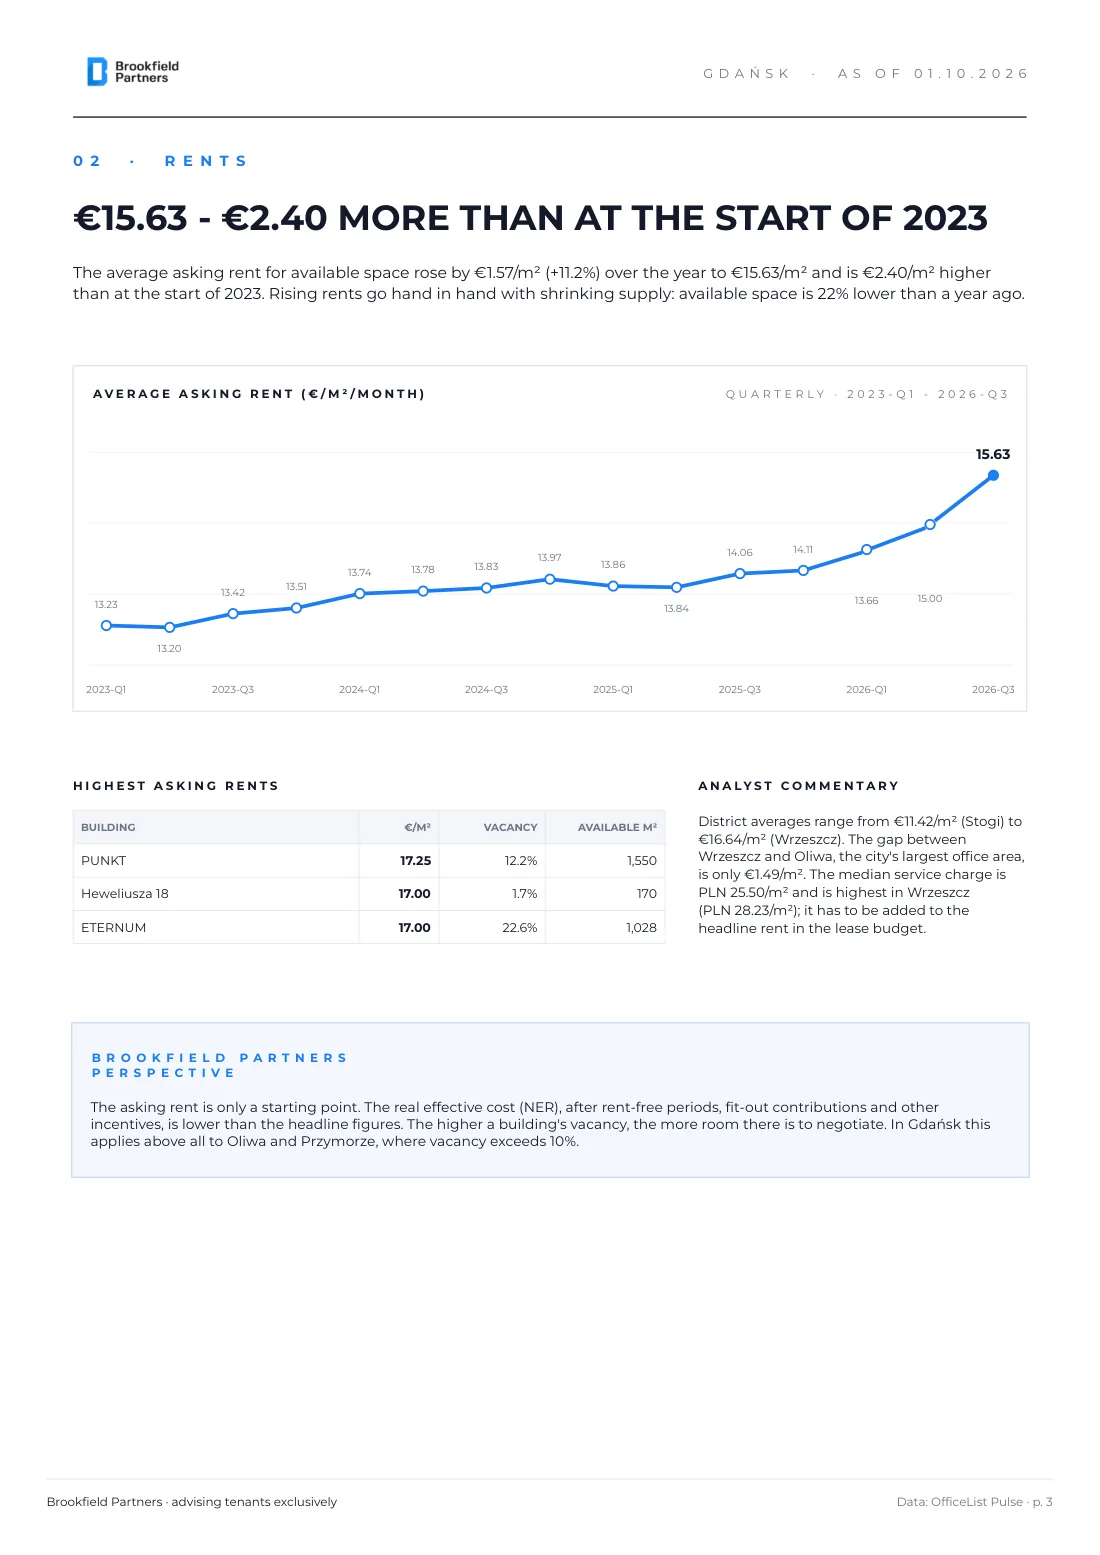
The average asking rent for available space rose by €1.57/sqm over the year, from €14.06 to €15.63/sqm, and is €2.40/sqm, or 18%, higher than at the start of 2023. For most of the series the rate stayed within €13.2-14.1/sqm. The clear jump came in 2026: from €13.66/sqm in the first quarter to €15.00/sqm in the second and €15.63/sqm in the third. Rising rents go hand in hand with shrinking supply, as available space is 22% lower than a year ago.
Average asking rent (€/sqm/month), quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| €/sqm | 13.23 | 13.42 | 13.74 | 13.83 | 13.86 | 14.06 | 13.66 | 15.00 | 15.63 |
Highest asking rents
| Building | €/sqm | Vacancy | Available sqm |
|---|
| PUNKT | 17.25 | 12.2% | 1,550 |
| Heweliusza 18 | 17.00 | 1.7% | 170 |
| ETERNUM | 17.00 | 22.6% | 1,028 |
District averages range from €11.42/sqm in Stogi to €16.64/sqm in Wrzeszcz. The gap between Wrzeszcz and Oliwa, the city's largest office area, is only €1.49/sqm. The median quoted service charge advance is PLN 25.50/sqm and is highest in Wrzeszcz at PLN 28.23/sqm. It has to be added to the headline rent in the lease budget.
Brookfield Partners perspective. The asking rent is only a starting point. The net effective rent, once rent-free periods, fit-out contributions and other incentives are taken into account, is lower than the headline figure. The higher a building's vacancy, the more room there is to negotiate. In Gdańsk this applies above all to Oliwa and Przymorze, where vacancy exceeds 10%.
Vacancy and availability: 8.17%, down 1.7 pp on a year ago
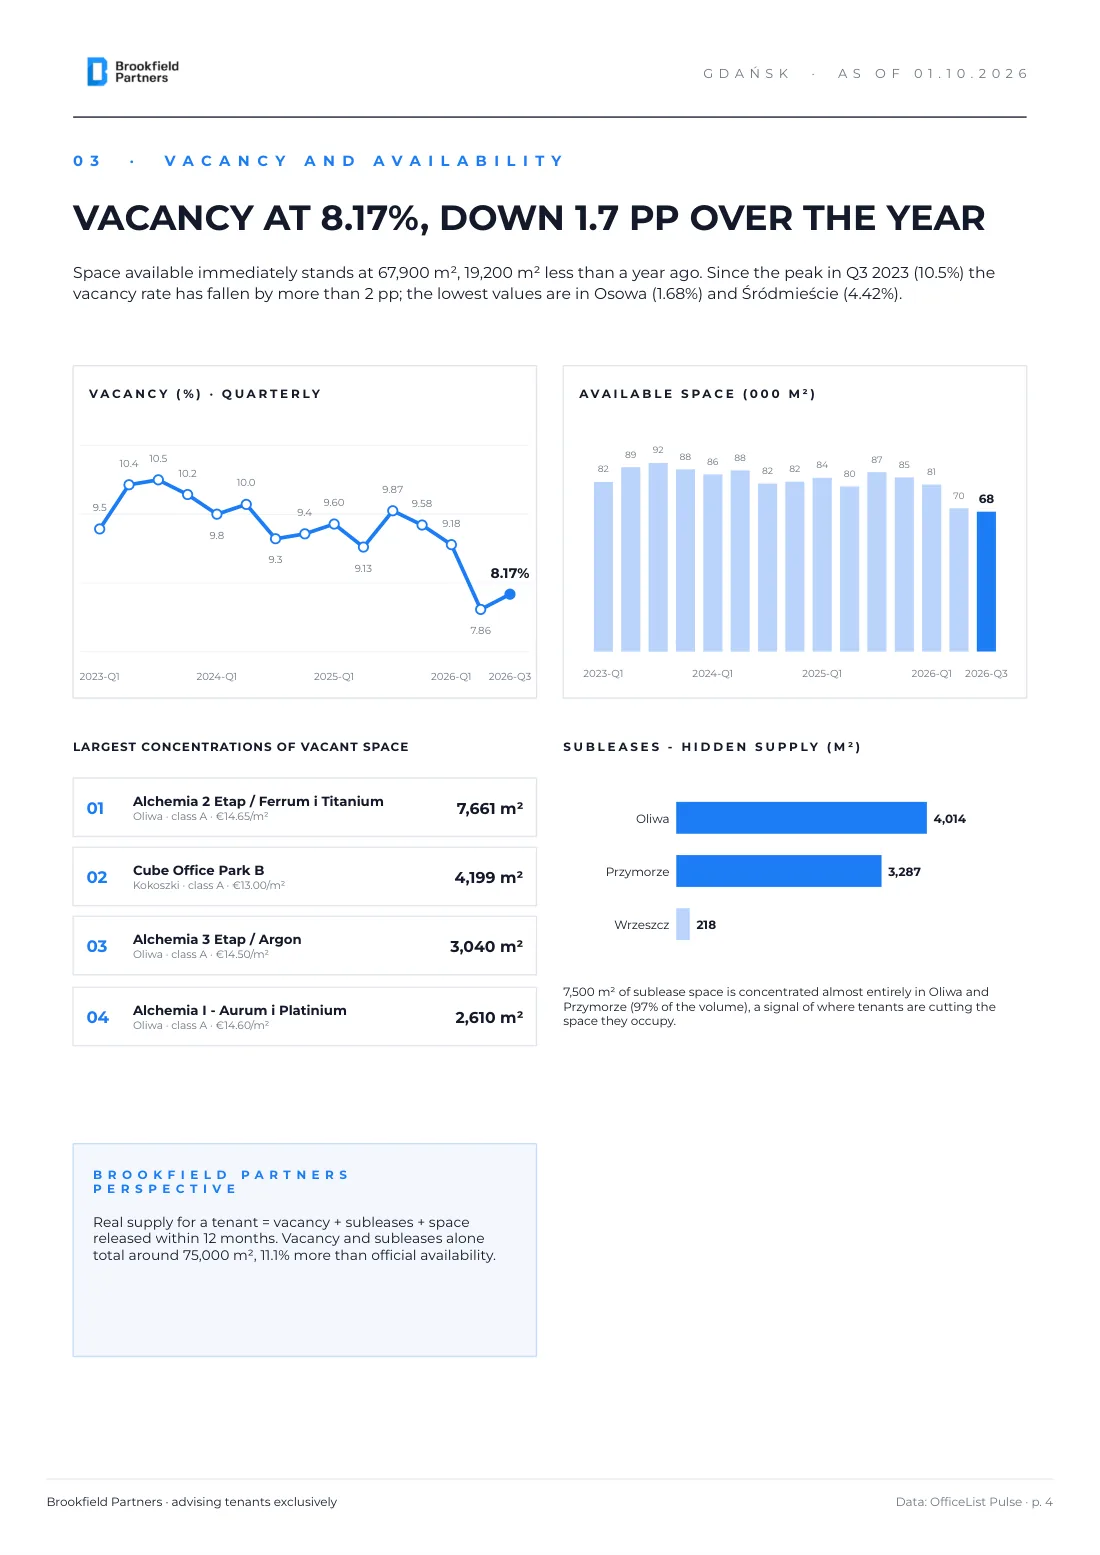
The vacancy rate fell from 9.87% in the third quarter of 2025 to 8.17%. Its lowest point in the series came in the second quarter of 2026, at 7.86%, and in the third quarter it settled just above 8%. Since the peak of 10.5% in the third quarter of 2023 the rate has fallen by more than 2 pp. Space available immediately stands at 67,900 sqm, 19,200 sqm less than a year ago. The least vacant space is in Osowa (1.68%) and Śródmieście (4.42%).
Vacancy rate and available space, quarterly
| Quarter | 2023 Q1 | 2023 Q3 | 2024 Q1 | 2024 Q3 | 2025 Q1 | 2025 Q3 | 2026 Q1 | 2026 Q2 | 2026 Q3 |
|---|
| Vacancy | 9.5% | 10.5% | 9.8% | 9.3% | 9.60% | 9.87% | 9.18% | 7.86% | 8.17% |
| Available (000 sqm) | 82 | 92 | 86 | 82 | 84 | 87 | 81 | 70 | 68 |
Largest concentrations of vacant space
| Building | Location | Class | Rent €/sqm | Vacant sqm |
|---|
| Alchemia 2 Etap / Ferrum i Titanium | Oliwa | A | 14.65 | 7,661 |
| Cube Office Park B | Kokoszki | A | 13.00 | 4,199 |
| Alchemia 3 Etap / Argon | Oliwa | A | 14.50 | 3,040 |
| Alchemia I - Aurum i Platinium | Oliwa | A | 14.60 | 2,610 |
There are 7,519 sqm on the sublease market, almost all of it in Oliwa (4,014 sqm) and Przymorze (3,287 sqm). These two districts account for 97% of the sublease volume, which shows where tenants are cutting the space they occupy.
Subleases - hidden supply by district (sqm)
| District | sqm |
|---|
| Oliwa | 4,014 |
| Przymorze | 3,287 |
| Wrzeszcz | 218 |
Brookfield Partners perspective. Real supply for a tenant is vacancy plus subleases plus space being released within a twelve-month horizon. Vacancy and subleases alone add up to around 75,000 sqm, 11.1% more than the official availability figure suggests.
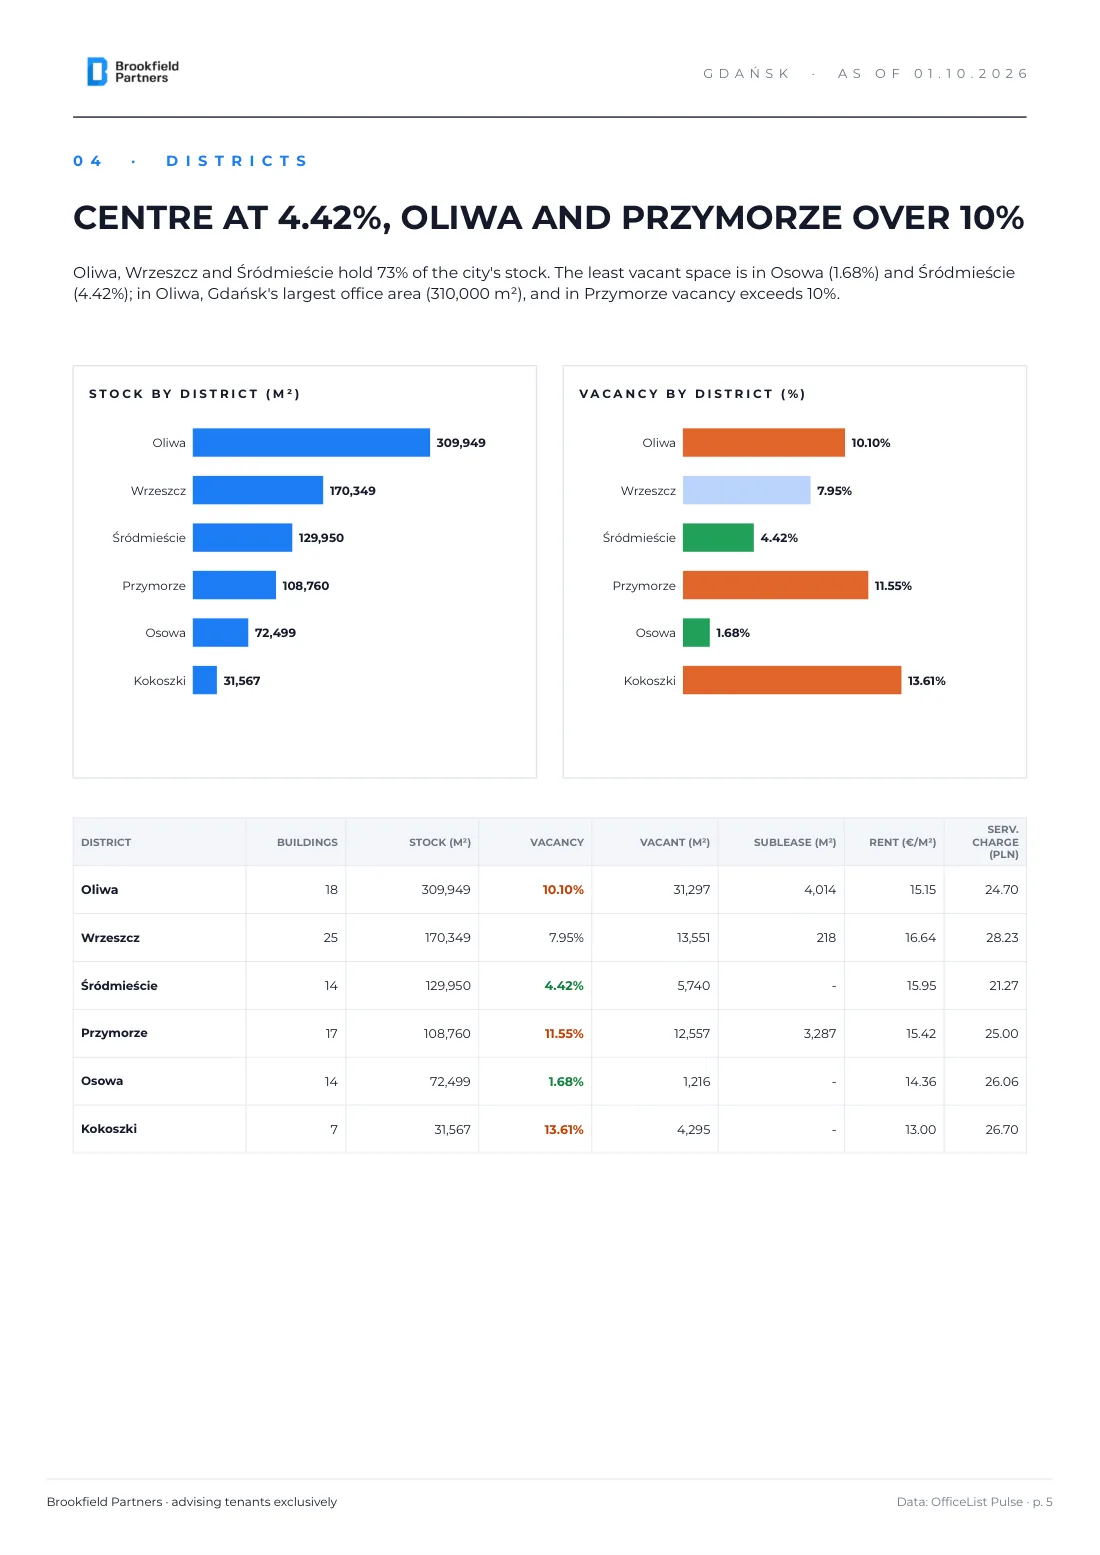
Districts: Śródmieście at 4.42%, Oliwa and Przymorze above 10%
Oliwa, Wrzeszcz and Śródmieście hold 73% of the city's stock. The least vacant space is in Osowa (1.68%) and Śródmieście (4.42%), which are now a landlord's market. In Oliwa, Gdańsk's largest office area with 310,000 sqm of stock, vacancy stands at 10.10%, and in Przymorze at 11.55%. Together these two districts hold half of the city's stock, and average rents there are 7-9% lower than in Wrzeszcz.
Gdańsk office market by district (as of 01.10.2026)
| District | Buildings | Stock (sqm) | Vacancy | Vacant (sqm) | Sublease (sqm) | Rent (€/sqm) | Service charge (PLN) |
|---|
| Oliwa | 18 | 309,949 | 10.10% | 31,297 | 4,014 | 15.15 | 24.70 |
| Wrzeszcz | 25 | 170,349 | 7.95% | 13,551 | 218 | 16.64 | 28.23 |
| Śródmieście | 14 | 129,950 | 4.42% | 5,740 | - | 15.95 | 21.27 |
| Przymorze | 17 | 108,760 | 11.55% | 12,557 | 3,287 | 15.42 | 25.00 |
| Osowa | 14 | 72,499 | 1.68% | 1,216 | - | 14.36 | 26.06 |
| Kokoszki | 7 | 31,567 | 13.61% | 4,295 | - | 13.00 | 26.70 |
Rent is the average asking rate for available space and the service charge is the median of quoted advances. The table covers the six districts with the largest stock.
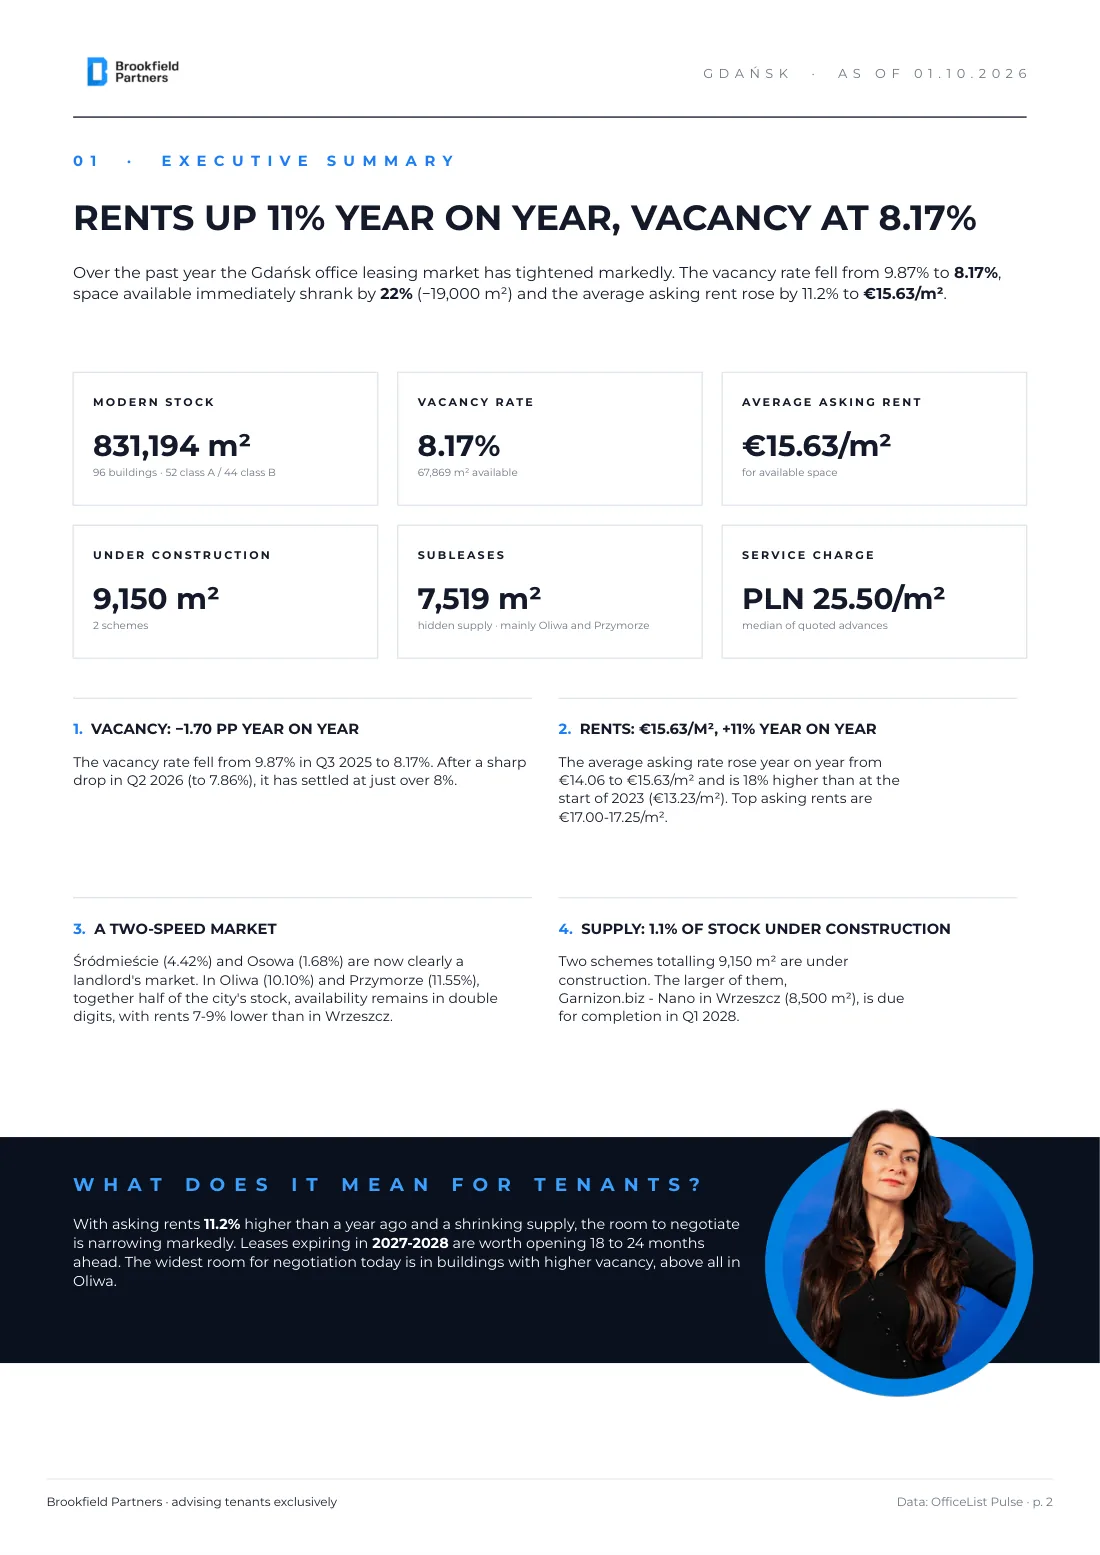
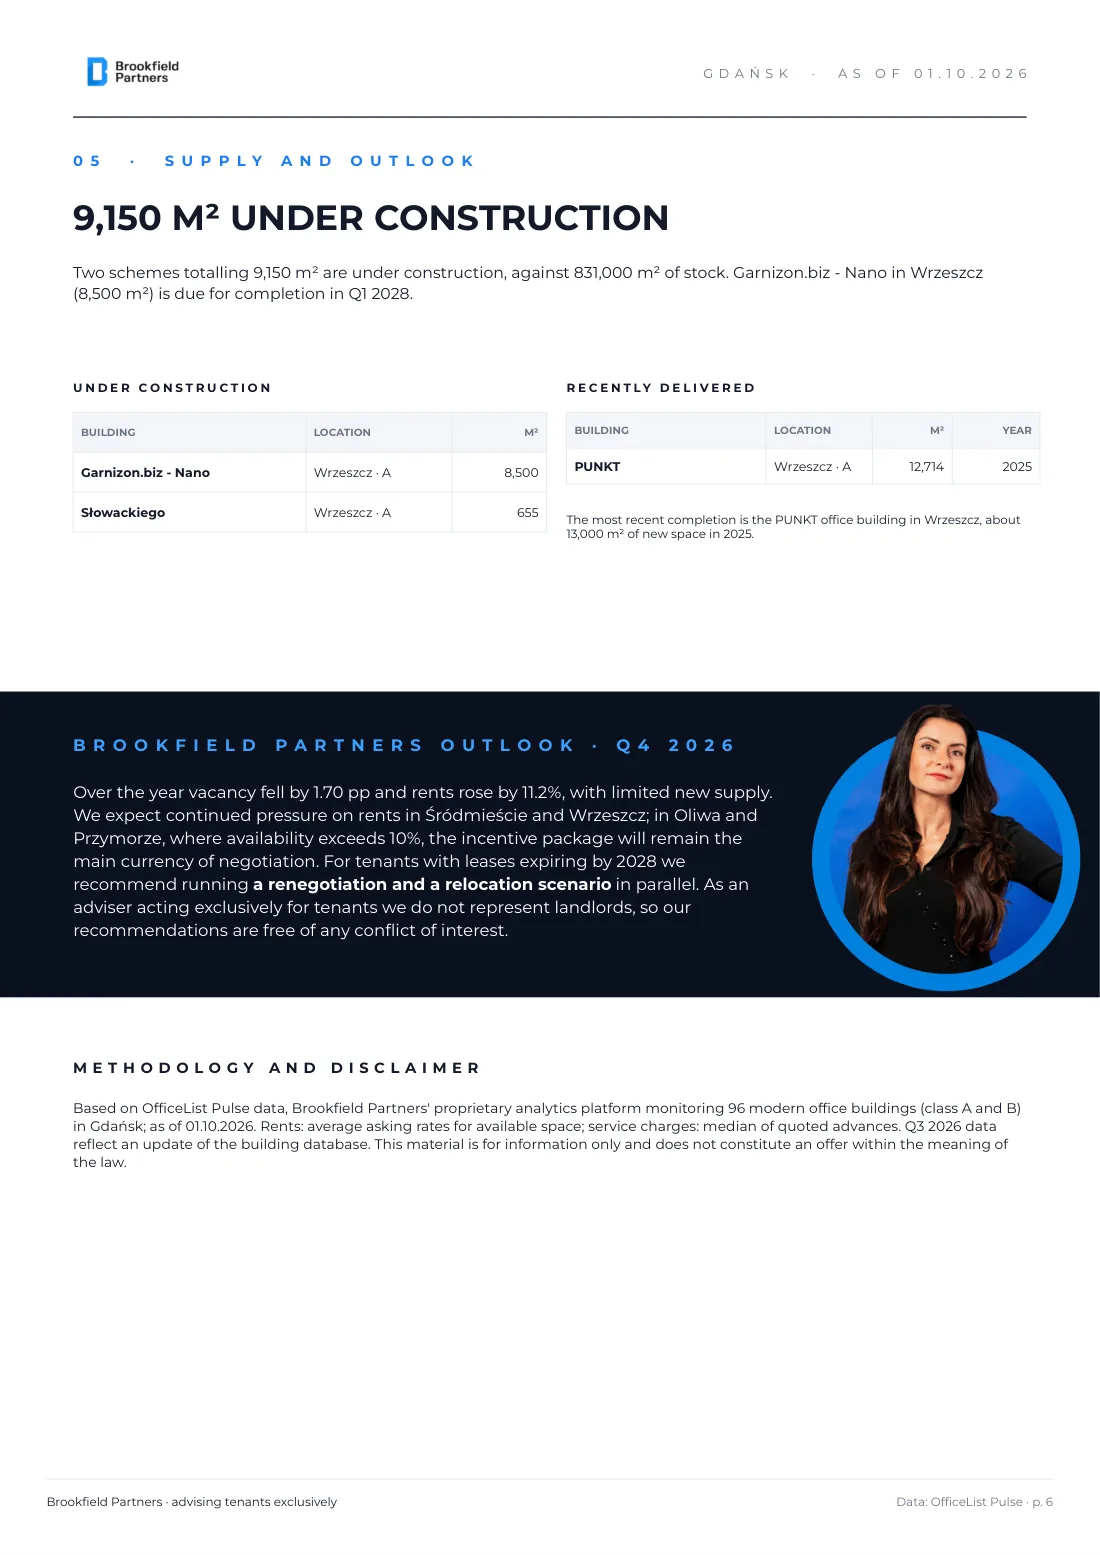
Supply: 9,150 sqm under construction, 1.1% of stock
Two schemes totalling 9,150 sqm are under construction, against 831,000 sqm of stock. The larger of them, Garnizon.biz - Nano in Wrzeszcz (8,500 sqm), is due for completion in the first quarter of 2028. The most recent completion is the PUNKT office building in Wrzeszcz, which delivered 12,714 sqm of new space in 2025.
Under construction
| Building | Location | sqm |
|---|
| Garnizon.biz - Nano | Wrzeszcz · A | 8,500 |
| Słowackiego | Wrzeszcz · A | 655 |
Recently delivered
| Building | Location | sqm | Year |
|---|
| PUNKT | Wrzeszcz · A | 12,714 | 2025 |
Brookfield Partners perspective (Q4 2026). Over the year vacancy fell by 1.70 pp and rents rose by 11.2%, with limited new supply. We expect continued pressure on rents in Śródmieście and Wrzeszcz. In Oliwa and Przymorze, where availability exceeds 10%, the incentive package will remain the main currency of negotiation. For tenants with leases expiring by 2028 we recommend running a renegotiation and a relocation scenario in parallel. As an adviser acting exclusively for tenants we do not represent landlords, so our recommendations are free of any conflict of interest.
Methodology
The report is based on OfficeList Pulse data, Brookfield Partners' proprietary analytics platform monitoring 96 modern office buildings in Gdańsk (52 class A and 44 class B), as at 1 October 2026. Rents are average asking rates for available space and service charges are the median of quoted advances. Data for the third quarter of 2026 reflect an update of the building database. This material is informational and does not constitute an offer within the meaning of the law.